Empowering the Next Generation of Women in Audio

Join Us

Union Benefits: Vacation and Health & Welfare

The last couple posts have talked about IATSE – details about the union and navigating benefits like Annuities and Pensions for Pink Contracts.

IATSE 101

Union Benefits: Annuity and Pension

In this post, we’re going to dive into the two other major benefits for Pink Contracts

Vacation and Health & Welfare

At a regular job you’d get benefits like healthcare and retirement through your employer, but in our industry we change employers regularly, sometimes multiple times a year, making that impractical. The union steps in to bridge that gap. They negotiate our contracts so the employers pay benefits in addition to our salary and the International manages those accounts via IATSE’s National Benefits Fund (NBF).

 The benefits we’re talking about are specific to Pink Contracts. These are the contracts for road crews on tour, show crews on Broadway, and some shorter runs like out of town pre-Broadway productions. Locals have their own set up for similar benefits, but they have different rules and requirements, which I don’t know much about, since I’ve only worked on Pinks.

The NBF handles four major categories: Annuity, Pension, Vacation, and Heath & Welfare. I’ll go over some of the basics, but there are plan summaries of all these accounts on the IATSE Benefit Plan website which can give you a much more detailed look at what all of these are.

Vacation

This is the most straightforward benefit. Each pay period, the company pays 5% of your salary earned into a fund that IATSE holds on your behalf. The money is supposed to act like the two weeks of paid vacation you’d receive at a normal job.

The money is taxed. You’ll see it on your paystub under earnings and then it will be withheld and sent to the IA benefits office. You do not get vacation on overtime.

Once a year, usually at the beginning of May, you will receive a check or direct deposit of that money, minus admin fees. Those have ranged from 2%-7% across the 15 years or so that I’ve received benefits. The fund is usually invested in short term fixed income to help offset the costs, but that doesn’t always work out, depending on the market.

If you want to se up direct deposit you can go through the NBF website and find the form under “Vacation” and “Forms and Applications.”

Health & Welfare

There are two plans under Pink Contract healthcare: Plan A and Plan C. 

If you’ve already read the previous blog about Pensions and Annuities, you can think of these plans in a similar way. Both are providing healthcare, just in different ways.

Plan A is the default option for larger tours and Broadway, and it offers a high level of coverage for healthcare, vision, and dental (spouses and dependents can also be included in these plans).

It operates somewhat similar to the Pension where you have to work a certain amount of days on a Plan A contract to be eligible for coverage. In this case, you maintain your coverage by working at least 60 days in a 6-month period. Every six months the count resets and you have to earn another 60 days to qualify for the next 6 months of coverage.

For example: let’s say you got your card and joined a tour at the end of August. Between load in, tech, and the first couple moves, you’re working six days every week for the next couple months, until you hit a layoff in November.

So, one week in August is 6 days, four weeks in September is 24 days (30 total), four weeks in October is 24 days (54 total), and three weeks in November is 18 days (72 total). This puts you over the threshold of 60 days in November.

As soon as you hit the threshold, the next month (in this case December) will be a processing or “look-back” month and the coverage will start the month after, so January 1st. Depending on when you hit 60 days, your accrual period and processing month with shift accordingly.

This extra month exists because the company has to send the payments to the benefits office and then the union makes sure your account is credited correctly. So there’s a built in month of time to make sure the office has time to get the correct number of days into your account. There are some times that days will get mixed up and you’ll have to reach out to the office to get things squared away. It’s a good idea to keep track of your pink contracts in case the NBF office needs them to verify employment.

Once your healthcare starts, your cycle would look something like this

Earn 60 days from December – May (processing in June) gets you coverage from July – December.

Then, earn 60 days from June – November (processing in December) for coverage from January – June.

Rinse and repeat each year. Your coverage might start in a different month, but that’s the general pattern. Earn 60 days in the accrual period, and you’re set for the next 6 months of coverage.
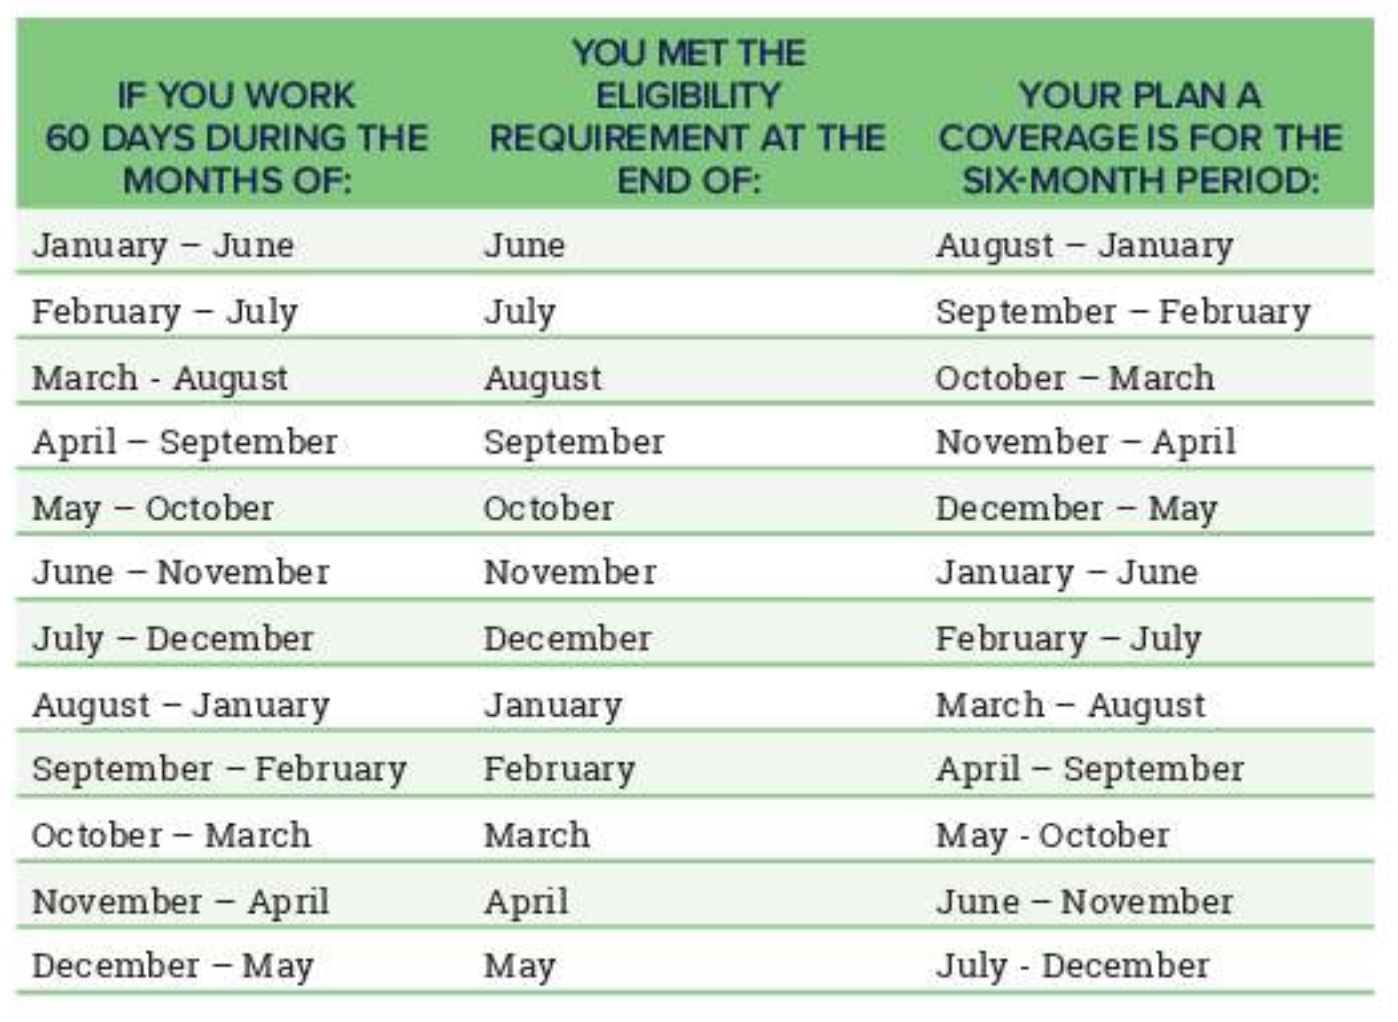
For a full-time job, this is pretty easy. You’ll typically earn closer to 120-140 days, well over the 60 day threshold.

Even though you earn so many extra days, you aren’t able to bank them or save them for later because Plan A relies on the majority of participants being full-time employees. Those extra days help subsidize the Plan A participants that only meet the minimum of 60 days.

That’s the gist of Plan A. Earn your days, keep your healthcare, enjoy low co-pays and deductibles.

If you don’t earn enough days in your 6-month period, your coverage will lapse until the requirement is met. You do have the option to pay for COBRA coverage on a monthly basis to bridge the gap, so you won’t completely lose your healthcare, but that can be expensive.

For example, let’s say your accrual period is May – October (coverage from December – May).

The show you’re on finishes up in May leaving you with 20 days in your account. June – October has some subbing or shop work, only some of which pays into Plan A (shop work will not). You have 20 days from May, plus 10 in June, 12 in July, 0 in August, 9 in September, and 7 in October for a total of 58 days.

Since you didn’t make 60 days between May and October, you won’t have enough days to qualify for coverage for the December – May block. At this point your account starts looking at the last 6 months, rolling forward until you make the 60 days.

Since May – October didn’t have enough days, now we look at June – November. We lose the 20 days from May, but get 15 in November (10+12+0+9+7+15) for a total of 53. Still not enough.

June – November doesn’t work, so next we look at July – December. We lose the 10 days from June, but get 20 in December (12+0+9+7+15+20) for a total of 63, which meets the threshold.

With your 60 days in the bank in December, your accrual period is now July – December, your processing month will be January, and coverage starts February 1st, with a lapse of 2 months.

This means you don’t have to wait a full 6 months to get your coverage back, you just start a new accrual cycle as soon as you earn 60 days.

As you can see, the all-or-nothing aspect of Plan A can be difficult if you’re not working full time or if you take on a lot of different jobs. You have to make sure you know when your accrual period ends and keep an accurate count of the days.

In NYC, everyone understands that people who are subbing still need their days to maintain healthcare. It’s not uncommon for a sub to reach out to the shows they’re covering and say they need a couple extra days to make their 60. Most people will be happy to give you extra days if you let them know you’re going to be a couple short. It’s up to you to stay on top of what you need and don’t be afraid to ask for help.

Plan C works a little differently. 

This is the healthcare that you’ll find on smaller tours and design contracts and is set up similarly to the Annuity where the benefit amount goes into an account and you have a little more control over how it’s utilized. Your employer sends the funds to the benefits office, and from there it goes into your personal CAPP account (Contributions Available for Premium Payments). This is money to pay the quarterly premiums or you can submit medical receipts for reimbursement if you have an excess balance (anything over 2 quarters of premium payments).

Unlike Plan A, this isn’t an all-or-nothing approach. If you don’t have enough in your account to pay the premium, you can self-pay the difference out of pocket and keep your coverage. Coverage starts as soon as you have enough in your account to cover one month of C-2 coverage, plus a $150 admin fee.
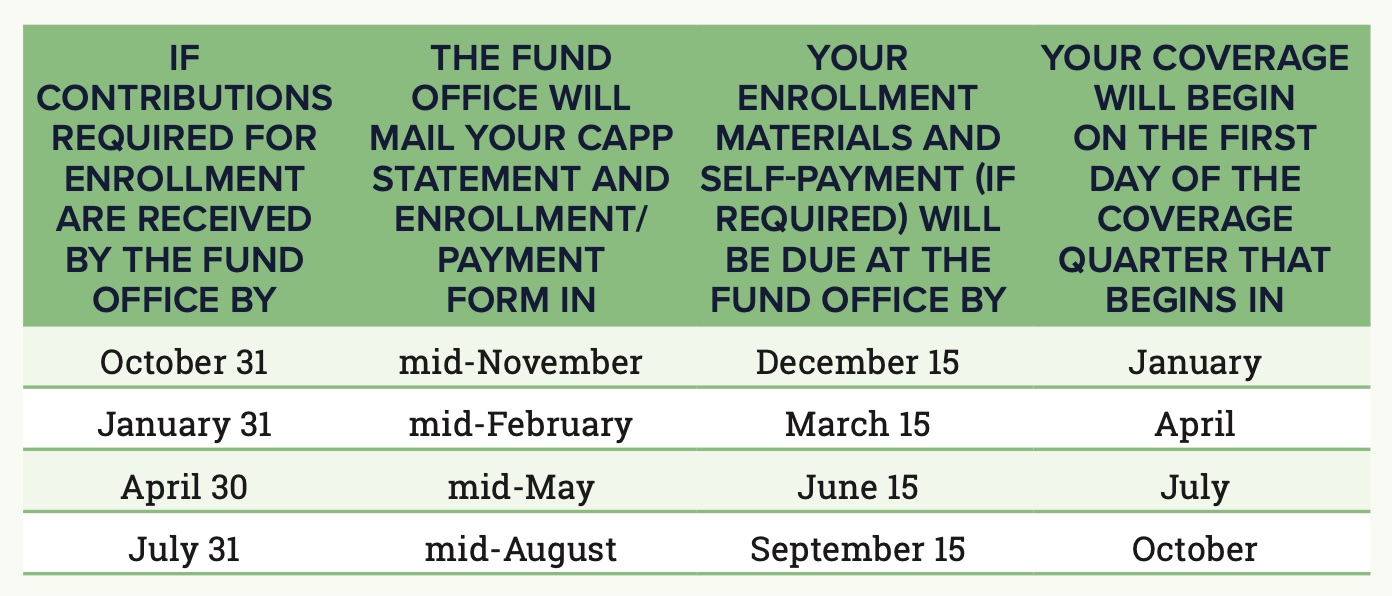
There are multiple tiers of coverage and you pay a quarterly premium to maintain your coverage

C-1 is a comprehensive plan with both vision and dental and has the lowest co-pays and deductibles. It’s probably the closest to Plan A coverage.

The quarterly premium is $5,964. So, if benefits are paid at the same rate as Plan A (which is $89/day) it would require 136 days of work to pay for a 6-month period (68 days per quarter).

C-2 is also a comprehensive plans with vision and dental, but has slightly higher co-pays and deductibles. Its quarterly premium is $3,045 or 70 days in Plan A contributions to pay for a 6-month period or 35 days per quarter. This is the option most stagehands on Plan C choose because it provides good coverage without the high quarterly cost of C-1.

C-3 is where coverage starts to noticeably decline. It requires you to use an in-network doctor for health-related appointments and hospital stays, and only includes basic preventative dental care and discounts on some vision services. Its quarterly premium is $2,232 or 52 days of Plan A rate for 6-months or 26 per quarter. This is a less common plan, but typically used if you’re not sure how much you will be working, but need to maintain some kind of health coverage.

C-4 in the paperwork is self-described as a “catastrophic plan with a high deductible.” It requires you to use in-network providers and doesn’t provide any dental, but has discounts on some vision services. Its quarterly premium is $1,293 or 30 days of Plan A rate for 6-months or 15 per quarter.

When you start working, you don’t have a choice of which plan you get; your contract will dictate which plan the employer pays into. As you continue on in your career, it’s more likely that you’ll work on a variety of shows, some that pay into Plan A (large contract tours, Broadway), others into Plan C (smaller tours, associate/assistant design work).

If you have an existing Plan C account and move to a show that pays into Plan A, you have two options: 

You can switch over to Plan A, and keep your Plan C account for medical reimbursements. You’ll have the Plan C account as long as there is money in it and there’s still some activity within a 2-year period (premium payments, reimbursements, or employer contributions).

Or you can opt to have your Plan A contributions redirected into your Plan C account. This means you keep your Plan C coverage instead of moving over to Plan A and the contributions go into your CAPP account which you can continue to use for quarterly payments or reimbursements. Plan A contributions are usually higher than Plan C, so you can bank the extra money to use in the future if you ever need to take time off or freelance.

Currently, there isn’t the option to request a Plan C account if you don’t already have one, so, if you’ve always been on Plan A, you just continue to stay on Plan A.

But why would you choose to take a lower tier of healthcare when your employer would pay into Plan A? How do you decide between the two plans if you have the option?

If you plan to spend most of your career in full-time employment, that makes it pretty easy to get the 60 days. If you need medications, have conditions that require consistent appointments and care, or if you have a family that relies on your healthcare, Plan A is usually the better option. The biggest downside to it is that 60-day requirement, and if that’s not a problem, it’s excellent healthcare.

The benefit of Plan C lies in its flexibility. If you plan to work on multiple kinds of contracts or have long stretches where you don’t work, Plan C works to your advantage. You keep your medical coverage, can use contributions whether they pay into Plan C or A (if you choose to redirect), and don’t have to stress yourself out counting days.

I spent most of my career on Plan A, and thankfully didn’t have to use it much. I had a Plan C account from an early tour that closed due to inactivity, and never thought much of it until I was ready to get off the road and move to NYC.

In 2023, I was subbing and freelancing. My first accrual period (Jan-June) had mix training and enough coverage that I made my 60 days quickly and didn’t worry about it much. The second period (July-Dec) was a different story. I did production for the 2nd National Tour of Mean Girls which took up most of my August and September, and that only paid into Plan C, so I just barely squeaked by with 70 Plan A days at the end of my 6 month accrual period.

Getting off the road was supposed to give me more control over my time and my work. It was supposed to mean that I could take time to visit my family, work on fun projects that kept me engaged, or take a vacation without worrying about my work schedule. The structure of Plan A and the stress of counting days felt like an incredibly limiting factor, so I swapped over to Plan C.

Plan A was great when I was on the road, and would have been while I was full-time on Outsiders if I’d kept that coverage. 

However, my priorities have shifted, and Plan C allows me the flexibility I envisioned when I left tour. I could walk away from Outsiders to help set up the tour and do an out-of-town tryout without worrying about how I’d make my days. After working on Dog Day Afternoon from this January through July, I can take a couple months off, probably sub a little, and work on an Off-Broadway show that won’t pay into my benefits. I can do all that and still maintain my health coverage for at least a year off the current balance in my CAPP account.

In the end, it’s what works best for your circumstances and goals. Each of us will have different needs that require a different application of the benefits that IATSE provides. Hopefully these couple posts were able to shed some light on how these work and what your options are. It’s a lot of information to digest, but knowing what your options are can help you plan for your future.
Union Benefits: Annuity and Pension

My last post talked about IATSE –  what it is, what it does, different paths to get into the union, and how different locals might interact. In my next two posts, we’re going to dive into benefits for Pink Contracts.

At a regular job you’d get benefits like healthcare and retirement through your employer, but in our industry we change employers regularly, sometimes multiple times a year, making that impractical. The union steps in to bridge that gap. They negotiate our contracts so the employers pay benefits in addition to our salary and the International manages those accounts via IATSE’s National Benefits Fund (NBF).

The benefits we’re talking about are specific to Pink Contracts. These are the contracts for road crews on tour, show crews on Broadway, and some shorter runs like out of town pre-Broadway productions. Locals have their own set up for similar benefits, but they have different rules and requirements, which I don’t know much about, since I’ve only worked on Pinks.

The NBF handles four major categories: Annuity, Pension, Vacation, and Heath & Welfare. I’ll go over some of the basics, but there are plan summaries of all these accounts on the IATSE Benefit Plan website which can give you a much more detailed look at what all of these are.

This post will be on Annuities and Pension, and another one will cover Vacation and Health & Welfare.

So let’s get into it:

Both Annuities and Pensions put money aside for your retirement. How they do it is different. 

An annuity puts your benefits into an account where that money is invested. At retirement you can withdraw all or part of the funds, or set up a plan where you’re paid a certain amount every month based on your balance.

A pension, on the other hand, counts the days you’ve worked in covered employment for the year and you earn up to one credit based on your count. At retirement you receive a payment based on how many credits you’ve earned and the rate at which those credits were paid.

Here we’ll dive into some details:

Annuity

Your annuity fund is similar to a 401k. Your employer is required to contribute a certain amount (each contract tier will use slightly different percentages), but you can also choose to make pre-tax contributions from your salary.

If you want to contribute, you have to fill out and submit a form. Some employers will include this form with the rest of your onboarding paperwork (W2, I-9, etc) when you’re starting a new show, but for others you’ll have to get it yourself and send it to your company manager. You can find it on the IATSE benefits website.

There are limits to what you personally can contribute to a 401k or other employer sponsored retirement accounts like annuities. For 2026 it’s $24,500, but it can (and does) change from year to year as the tax code tries to compensate for inflation. Make sure you double check what the limit is before you fill out the form. Personally, I usually try to contribute at least 5-10% of my salary, depending on the contract.

As a quick rule to figure out how much I can contribute: I’ll take the limit ($24,500) and divide by 50 weeks (assuming I’ll take some vacation time). That comes out to $490 for 2026. If I know my salary (the rate for a head of department on Broadway is currently $3,200), I can see that $490 is a little over 15% of $3,200. That means if I’m working full time on that salary, I can contribute up to 15% without going over the limit. So, my normal 5-10% will be fine.

Your annuity account collects the contributions from you and your employer and invests them in one or more funds provided by the investment company.

Currently, the Pink Contract annuities are taken care of by a company called Principal. A few years ago it was Wells Fargo. The companies will change, but the funds typically stay the same. The benefits website provides a link to the company’s website where you can create an account to look at your balance and choose which funds your money is invested in.

There are a variety of different accounts:

Fixed Income which are things like bonds or CDs (Certificate of Deposit). These are lower yielding, but typically very consistent.

Equity accounts which follow companies in different categories: Large which are big brand-name companies you’d recognize, Small/Mid which are usually lesser known companies that have room for upward mobility, or International, which are foreign companies. These equity accounts tend have more risk/reward than fixed income because companies either do well and grow, or fail and get removed from the market.

Target Retirement Funds have several options depending on the year you plan to retire (assume when you’re 65). The asset allocation of the fund will shift over time from more aggressive (stocks) at the beginning for growth, to more conservative (fixed income) as you get closer to your retirement age, providing stability.

By default, your money will go into an “IATSE Annuity Balanced Fund.” This is somewhere between fixed income and equity, so more conservative returns, but fairly stable in general.

If your eyes completely glazed over as soon as I said “Fixed Income,” I’d recommend you direct the fund to invest in the Target Retirement fund that best lines up to your age bracket, and forget that it exists.

The only reason I say forget it is because your account will fluctuate with the stock market and other investments. Obsessing over which fund makes more money on a given year is sure to drive you nuts, and many armchair experts can do more harm than good if they keep trying to jump in and out of funds.

Once money starts going into this fund it is yours and it will continue to exist, tracking the success of your investments until you hit 65, even if you leave covered employment. At 65 you can choose to receive the amount of the account as a lump sum (either in its entirety or just part of it), or have the account converted into an annuity that will pay you a certain amount guaranteed for the rest of your life.

There are a couple things you can do outside the normal bounds of the annuity

You can take early or hardship withdrawals, which come with fees and taxes, so they’re typically not recommended, unless there is an emergency or urgent need. I know of a few people who opted to make those withdrawals during COVID.

The other option is similar to having a 401k with an employer that you’ve left. If there are no contributions to your annuity for 6 months or more, you can take your annuity balance and roll it over into a personal IRA (Individual Retirement Account) without incurring a tax penalty. This mean the company that manages the annuity will send all the money in your account to the your bank and they deposit it into your IRA where you can decide what to invest it in.

Just make sure it’s a rollover and they don’t send the money to you. That comes with taxes and fees that won’t happen if the banks handle it.

If you don’t have an IRA, I strongly suggest you open one. This is similar to an annuity, but you’re the only one who’s contributing and you have full control over where the money is invested.

Pension

Pensions are a thing of the past for many people. For earlier generations you’d work for a company for 40 years and then retire with the promise of a guaranteed monthly payment based on how long you’d worked for the company. Some unions, like IATSE, still have pension programs for their members, giving you one more resource to build a comfortable retirement.

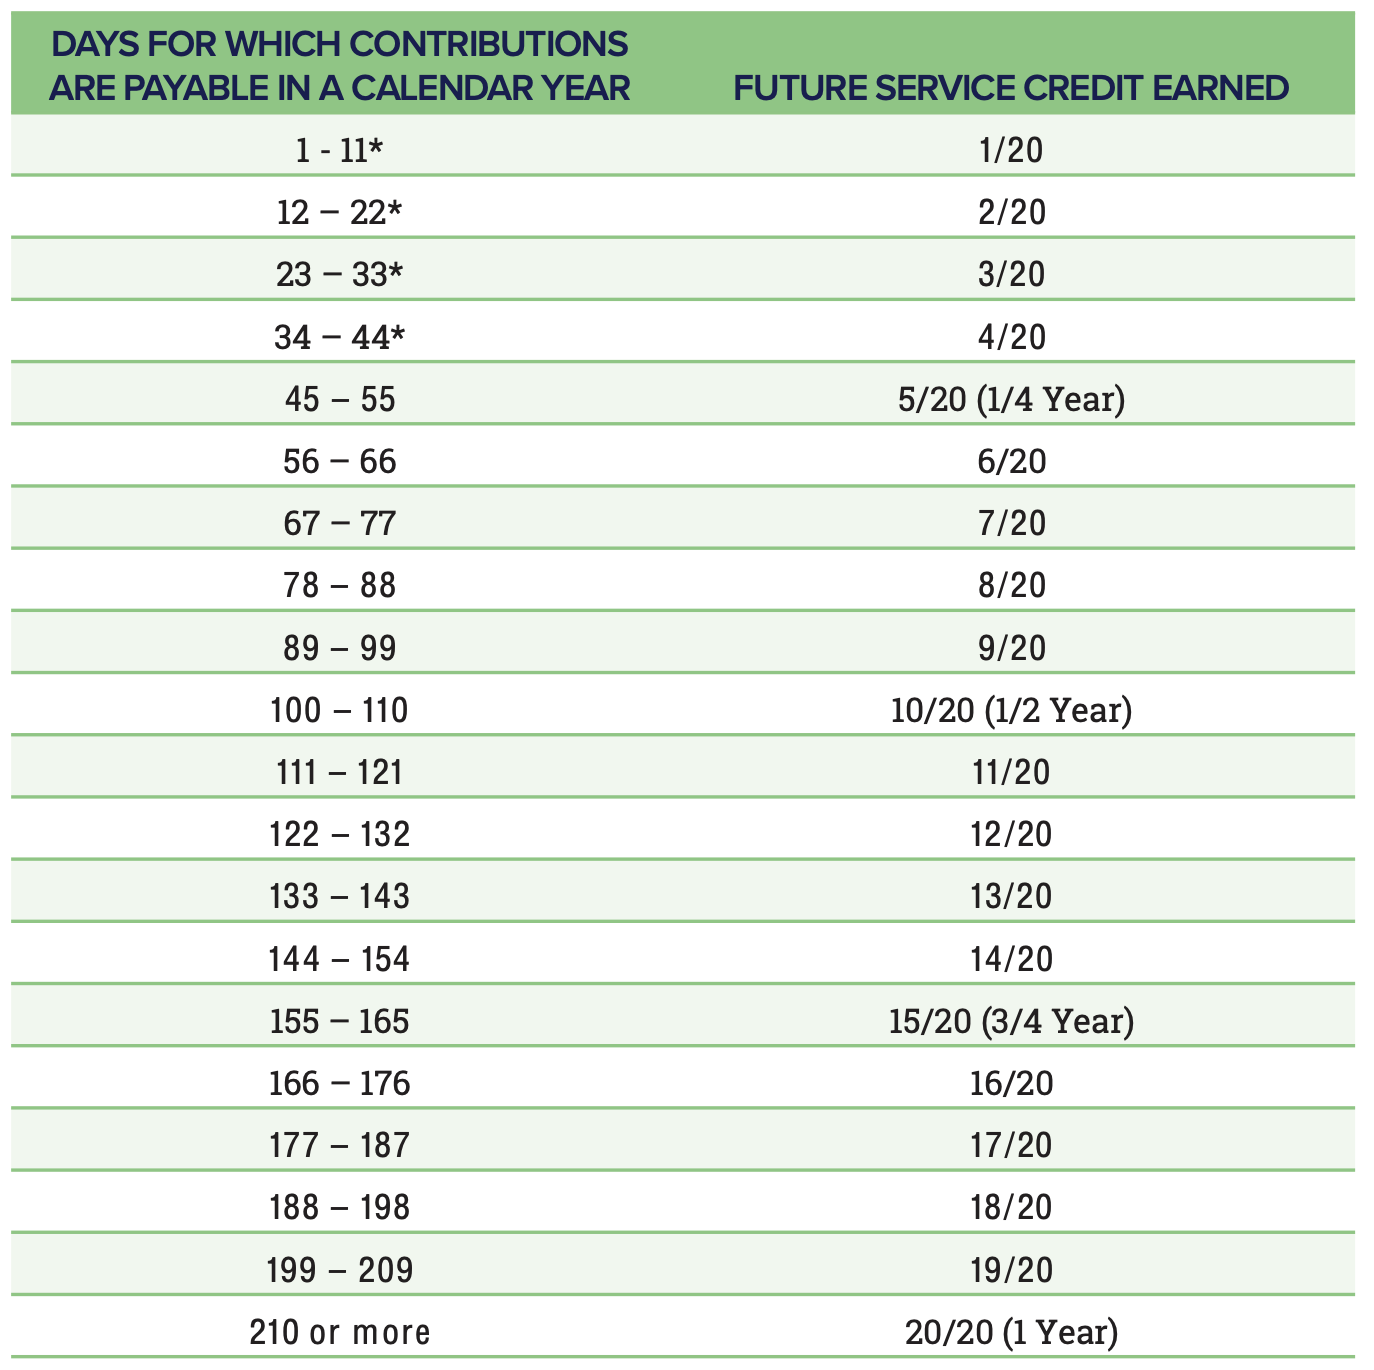
Each day worked counts towards a credit in your pension account. You can earn up to 1 credit per year if you work 210 days or more. If you work fewer days than that, you get partial credit. Your retirement benefits count up to a maximum of 25 credits.

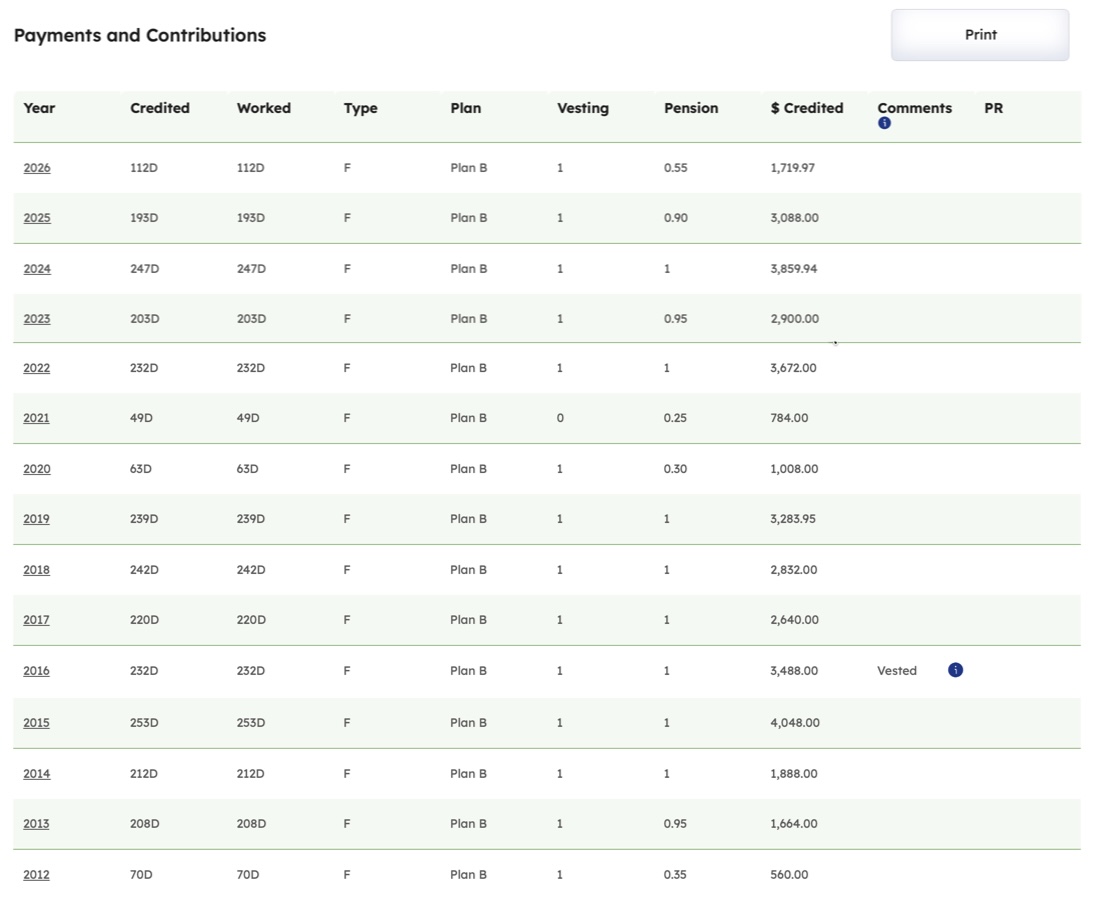
This is what my pension history looks like:

2012 was when I joined IATSE and started touring in August. There was no way I could make it to 210 days, but I got the partial credit for the days I did work.

2013 was split between two tours with a summer off and enough layoff weeks that I didn’t quite hit the 210 day mark.

From 2014 to 2022 I was almost constantly on the road and earned the full credit each year (ignoring 2020/21 for COVID).

2023 was when I moved to NYC. Between subbing, production work, and shop builds, I worked well over 210 days, but not all of the jobs paid into my pension, so I ended up with 0.95 credits for the year.

Things like shop work pay well, but if you’re over-hire (only there for the shop build and not on the show run), you don’t receive benefits. Similarly with some design contracts.

For 2024 I was on Outsiders the entire year and made my full credit.

In 2025 I left Outsiders in the summer, look a long vacation, and got back to subbing and shop work. In the fall, I was the Assistant Designer for the Outsiders tour, but that contract paid into Healthcare and Annuity benefits, but not the Pension. So I got close, but not quite to the full 210 days.

2026 is still up in the air. I was full-time on Dog Day Afternoon from January to mid-July, but the fall and winter will likely be scattered with some time off, subbing, and shop work, so it’ll likely be similar to my 2023 year.

I’m not concerned about only getting partial credit for some years. Pension benefits for pink contracts are capped at 25 credits, so looking at the math: I’m 36 years old with 12.25 credits. That means I have a little under 30 years (until I’m 65) to earn the other 12.75.

That feels like plenty of time so I don’t have to rush. I have the freedom to take shop work, go on vacation, or opt to take jobs like the designer contract for the Outsiders tour.

You may have noticed another column next to the Pension credits called “Vesting.”

Unlike the Annuity, where the account is yours as soon as the first deposit goes in, the pension program requires you meet a threshold before you’re eligible for benefits.

To earn an Vesting Credit, you have to work at least 75 days in covered employment in that year, and you need 5 Vesting Credits to become eligible for pension benefits. Once you are vested, you have a guaranteed right to your pension at retirement, even if you leave covered employment. Any year you get 0.40 credits or more, you’ll automatically hit the days needed for the vesting credit.

So, say I made a complete career shift next year. I’m still vested in my pension with 12.25 credits, so at 65 I would receive benefits based on those credits, even though I left the industry for 30 years.

When you retire, your benefits are calculated on how many credits you have (up to 25) and the pay rate of the last 3 years. 

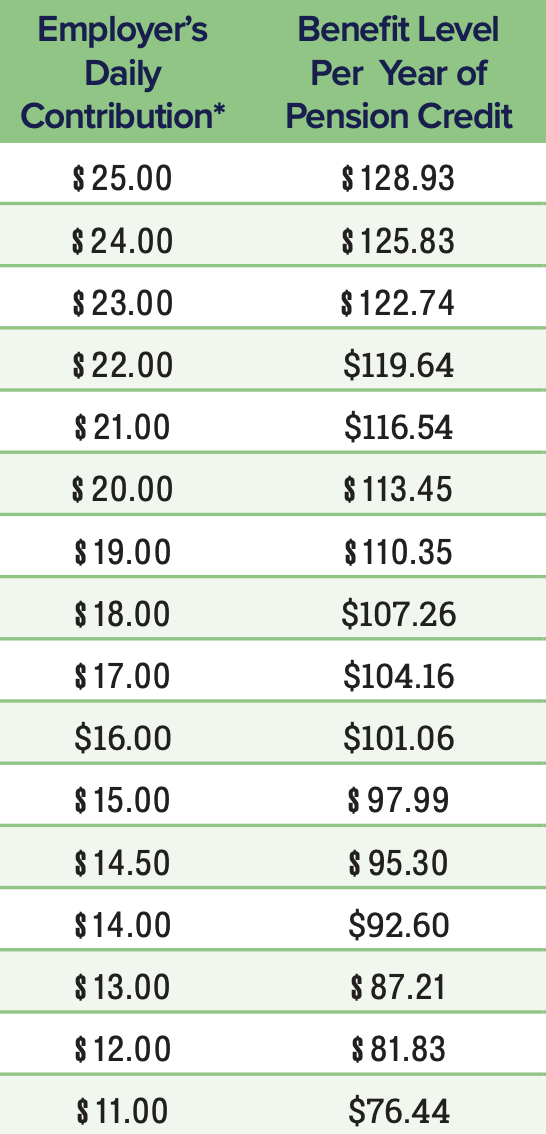
Each contract pays a different rate (bigger contract, typically higher rate), and for the current contract cycle a Full Pink contract pays $16.00/day, while a Modified Pink pays $12.00/day, and a Bus & Truck contract pays $8.00/day.

There’s a chart in the formal Plan B description (found on the NBF website or below), and we’ll run two scenarios:

First, let’s follow my previous example. I left the industry with 12.25 credits, and spent my last three years on a Full Pink contract with a $16 rate.

The chart converts the $16 rate into a $101.06 benefit, and that gets multiplied by my 12.25 credits. My monthly benefit at retirement would be $1,237.98.

Or, let’s say I continued working and earned 30 credits and my last three working years had 2 years at the $12 rate, and 1 year at the $16 rate.

The chart converts the $12 rate to $81.83 in benefits and the $16 rate is still $101.06.

The monthly benefit in retirement would be the average of the benefit for my last 3 years: (81.83 + 81.83 + 101.06) / 3 = 88.24. Then that result is multiplied by my credits, up to 25, even though I technically earned 30.

So, 88.24 x 25, for a total of: $2,206 per month.

As you can see, your benefits will change depending on how many credits you have and what kind of contracts you worked on. They only use the last 3 years to calculate because they assume your pay rate will be the highest at the end of your career.

One very important tangent: you should actively plan for your retirement, no matter what life stage you are in or what benefits you expect to receive from your job. If you’ve just entered the workforce, retirement probably seems impossibly far away but that also means you have the advantage of time. Time to let your money grow, time to try things, make mistakes and get back on track. Learning to pay attention to your money is one of the best life skills you can acquire.

I got a wake up call when I was on tour. I listened to men across the country talk about how they hadn’t saved anything for retirement, so they’d be working until they died. Watching men in their 70’s and 80’s still working, struggling to push boxes lit an absolute inferno under me. I made sure I had a plan for my future so I wouldn’t have work until my body gave out.

I know that’s a lot of technical jargon to digest, and retirement is something that’s hard to conceptualize when it’s decades away. But learning what your benefits are and how they work can help you make informed choices and send you down the right path for success.

IATSE 101

If you end up working in the theatre industry, especially if you want to work on tour or in NYC, chances are good you’re going to work with or become part of a union.

Actors and stage managers are both in Actor’s Equity Association (A.E.A.), truck loaders are part of the Teamster’s union, and musicians join A.F.M. (American Federation of Music). Company managers are a part of ATPAM (Association of Theatrical Press Agents and Managers) and designers are USA 829, both of which are a part of IATSE (International Alliance of Theatrical Stage Employees), who primarily represents stagehands for theatre and film.

IATSE has hundreds of chapters across the US and Canada called “locals.” Local 1 is NYC, Local 2 is Chicago, up into the 900’s with Local 918 in Anchorage. Some cities have multiple locals, so you might have one for theatre stagehands and another for film crews, or sometimes the departments themselves are separate with one local for hair, wardrobe, and make up and another for carpentry, props, and electrics. Technically, sound is a subset of electrics, but that rarely comes up unless your Head LX wants to joke that they’re actually your boss or you need to grab some electricians to help sound in a “push by department” city.

Each local has a different process for how you join and many have their own benefit programs for health care and retirement. It gets complicated quickly, so we’re going to take an in-depth look at my own IATSE local, since I know it’s programs the best: ACT. 

ACT (Associated Craft Technicians) started as a bit of a catch-all, but today is mainly comprised of touring stagehands who weren’t already IATSE members when they went on the road. The original thought was that we would be on the road for a while, then find a place to settle down and transfer into the nearest numbered local.

The reality ended up that many of us planned to stay on the road indefinitely or settled in areas like NYC where the local doesn’t accept direct transfers. Eventually there were enough ACT members that the International recognized us as our own local and we now have representation at conventions and meetings.

If you plan to be in one place for the next couple years, take a look at IATSE’s Local Union Directory. It’ll give you information on your area’s local and who to contact if you’re looking for more information on how to join, since this post is going to cover a different part of IATSE.

So you want to tour or work on Broadway, which means you’ll eventually have to join IATSE. How do you become part of it?

For tour, this is fairly straightforward: when you join a production (usually through a company like NETworks, Crossroads Live (once Troika), Worklight, or Feld Entertainment), if you aren’t already a member of IATSE, the company will buy you into the union as an ACT member. They’ll pay your dues for the rest of the current year, then prorate your paycheck to reimburse that cost. For me, they paid for two quarters since I joined the tour in August and took out a quarter of the dues for two paychecks.

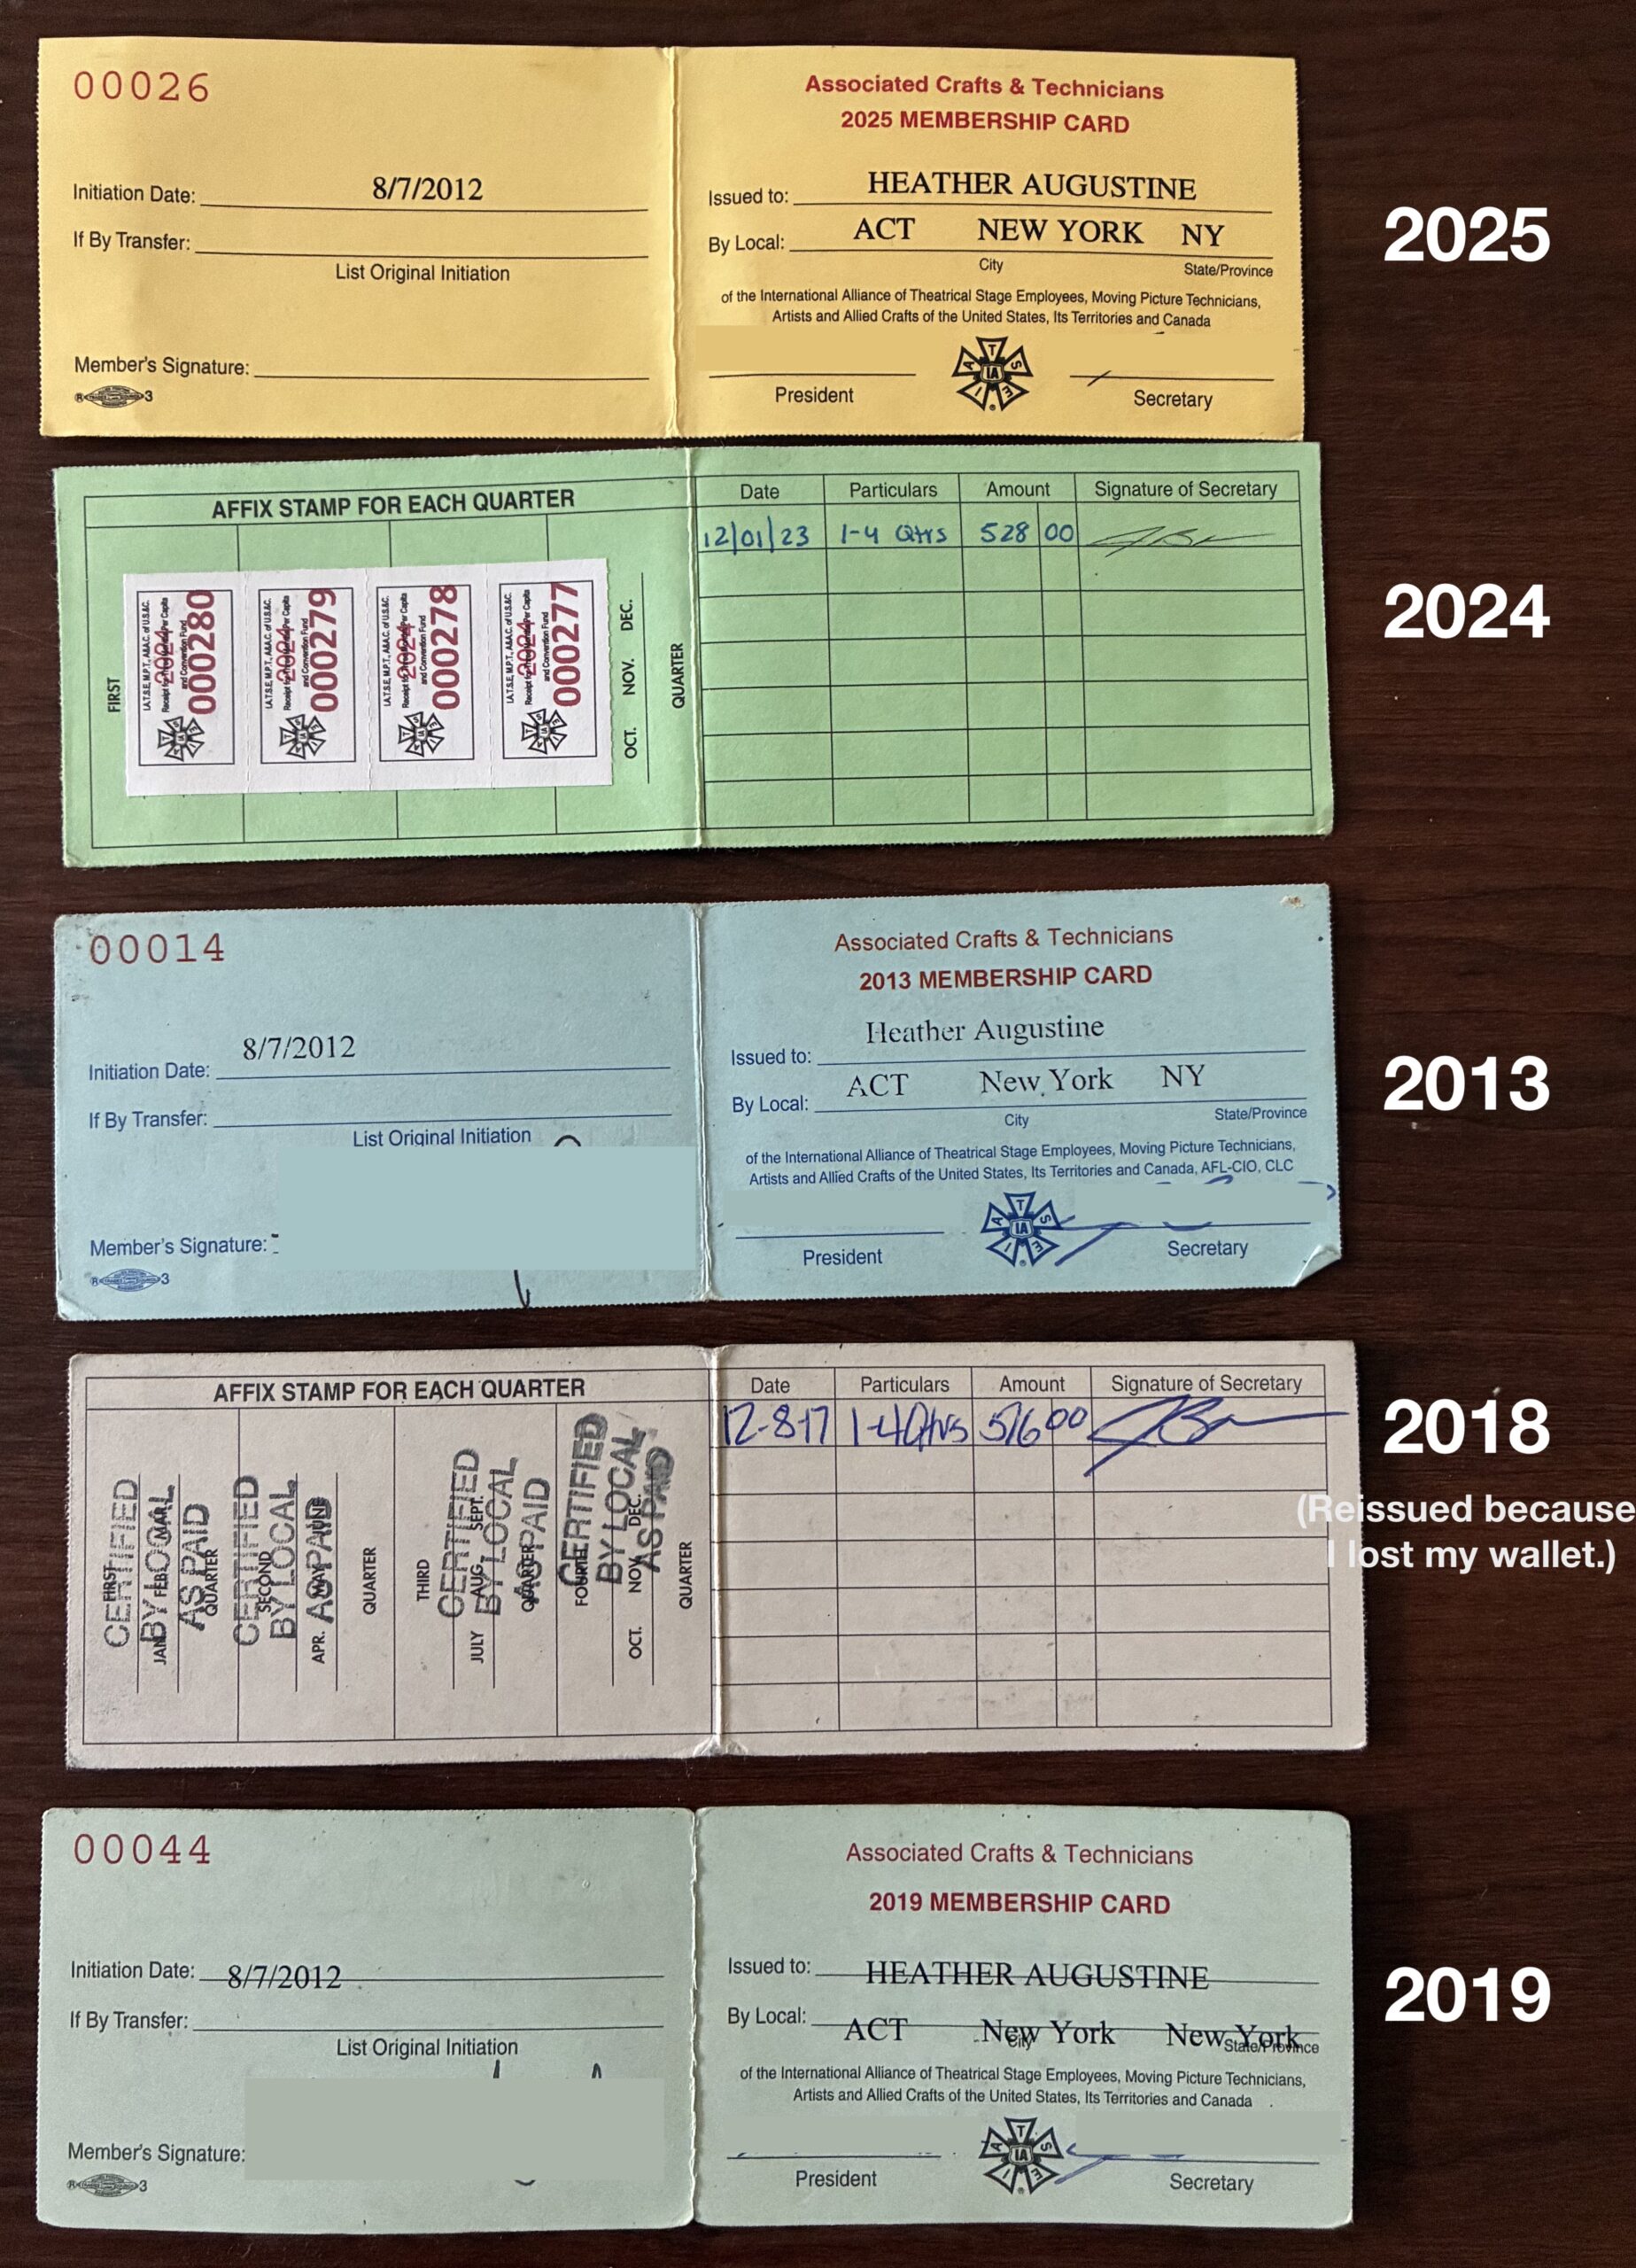
For context, my ACT dues for 2026 was $540, or $135 per quarter, and each year it goes up by a dollar or two per quarter. ACT members and those on the road typically have to pay for the full year of stamps at once.

Once you have your card, you’re the one responsible for contacting the office and paying your dues for the upcoming year. You’ll usually get a letter and emails to remind you in October or November, so try to pay them before the end of the year, and the office will usually send your new card a couple stops ahead. That way you don’t have to play catch up if it makes it to a city after you’ve already left.

Other locals have different requirements. Some have apprenticeship programs or classes to take. Local 1 in NYC requires that you earn a certain amount of money on their payroll for three consecutive years before you’re eligible to be inducted. Usually this requires working load ins and outs or subbing on show tracks.

Broadway and tour crews work on Pink Contracts. These are positions that can be staffed by an IATSE member, no matter what their local is. This is how I can live and work in NYC while still being a member of ACT, not Local 1.

This is because Broadway and tours operate where you have a two distinct sets of crews: a show crew and a house crew. 

In NYC, the house crew is Local 1 and paid by the management that owns the theatre itself. The show crew are on a Pink Contracts, paid by the production company of the show itself. The house crew stays with the theatre, show after show, while those on a Pink will move from theatre to theatre as they work on different shows.

Each show is limited to a certain amount of pink contracts, so those are often positions like automation, pyro, props, mixers, and A2s. Positions that either designers or the production company want some say in hiring.

These allowances were made by Local 1 because shows need specialty positions: you might have a great house carpenter, but not someone who knows the automation system being used. Props people might need specific skills to repair items or handle firearms. Sound is a subset of the Electrics department, so you don’t have a Head Sound in the building on Broadway, let alone someone who can program a console or mix a show the way a specific designer wants.

For a musical like Outsiders the Broadway crew broke down like this: 

House Crew:

Carpentry (2): Head Carp, Flyman

Electrics (4): Head Electrician, Assistant Audio, 2 Followspot Operators

Props (2): Head Props, Assistant Props

Show Crew:

Carpentry (1): Head Carp/Automation

Electrics (4): Head Electrician, Pyro Op, Head Audio, Assistant Audio

Props (2): Head Props, Assistant Props

For a play like Dog Day Afternoon, there were different crew needs:

House Crew:

Carpentry (2): Head Carp, Flyman

Electrics (2): Head Electrician, Assistant Audio

Props (1): Head Props

Show Crew:

Carpentry (1): Head Carp/Automation

Electrics (2): Head Electrician, Head Audio

Props (1): Head Props

It was a smaller show with no follow spots, fewer deck tracks for props and carpentry, and no Pink A2.

Wardrobe, Hair, and Make up (sometimes collectively abbreviated to as WHAM) are under different contracts in NYC that aren’t Pink or Local 1, but you’ll usually have a head and an assistant in each Wardrobe and Hair, a Make up artist if you have some special effects, plus multiple dressers, a stitcher, and a laundry person.

Your house crew has to match or exceed the number of pink contracts for everything including show calls, rehearsals, and work calls.

Tour crews are similar in most respects. Where they differ is that show crew for WHAM are on the same pink contracts as the rest of the crew, sound is treated as its own department, so you’ll have an actual house Head Audio in most cities, and there are more people in general on the crew.

Show crews for tours might break down like this: 

House Crew:

Carpentry (6): Head Carp, 2 Flyman, 3 Deck Carps

Electrics (4): Head Electrician, Deck Electrician, 2 Followspot Operators

Audio (2): Head Audio, Assistant Audio

Props (4): Head Props, 3 Deck Props

Wardrobe (8-10): Head, Laundry, Stitcher, Dressers

Hair (1-2): Stylists

Show Crew:

Carpentry (4): Head Carp, Automation, Flyman/Rigger, Deck Carp

Electrics (3): Head Electrician, Spot Op, Deck Electrician/Video Tech

Audio (2): Head Audio, Assistant Audio

Props (2): Head Props, Assistant Props

Wardrobe (3): Head Wardrobe, Assistant Wardrobe, Star Dresser

Hair (2): Head Hair, Asst Hair/Make up

There are more people on a road crew because they have to know the show tracks and teach it to the local crew, as well as have enough people to give direction and load the show in. You can look up any of the shows under an IATSE contract and see what their crew requirements are, as per their Yellow Card, or the documentation of union status and labor needs.

Taking a look at the actual contracts, the same structure of the Pink Contracts that apply to Broadway, also cover tours. 

However, while there is only one contract for Broadway, there are multiple for tour.

There are a set of contracts for League Producers for when the same people who produced the Broadway version are sending out the tour. There’s another set for the production companies like NETworks, Crossroads Live, and Worklight who typically take the shows and trim them down to make it easier to tour in smaller markets.

These contracts have different tiers, each with different minimums for salaries and benefits.

“Full Pink” contracts have lower minimum salaries, but similar benefits as a show on Broadway. “Modified Pink” is a step down with lower in benefits and minimums for a theoretically smaller show.

“SET” or Short Engagement Tours are another step smaller than the Modified, and “Bus and Truck” tours (which originated from when a tour was one bus for cast and crew and one truck of gear) now denotes a small tour that does mostly one-nighters.

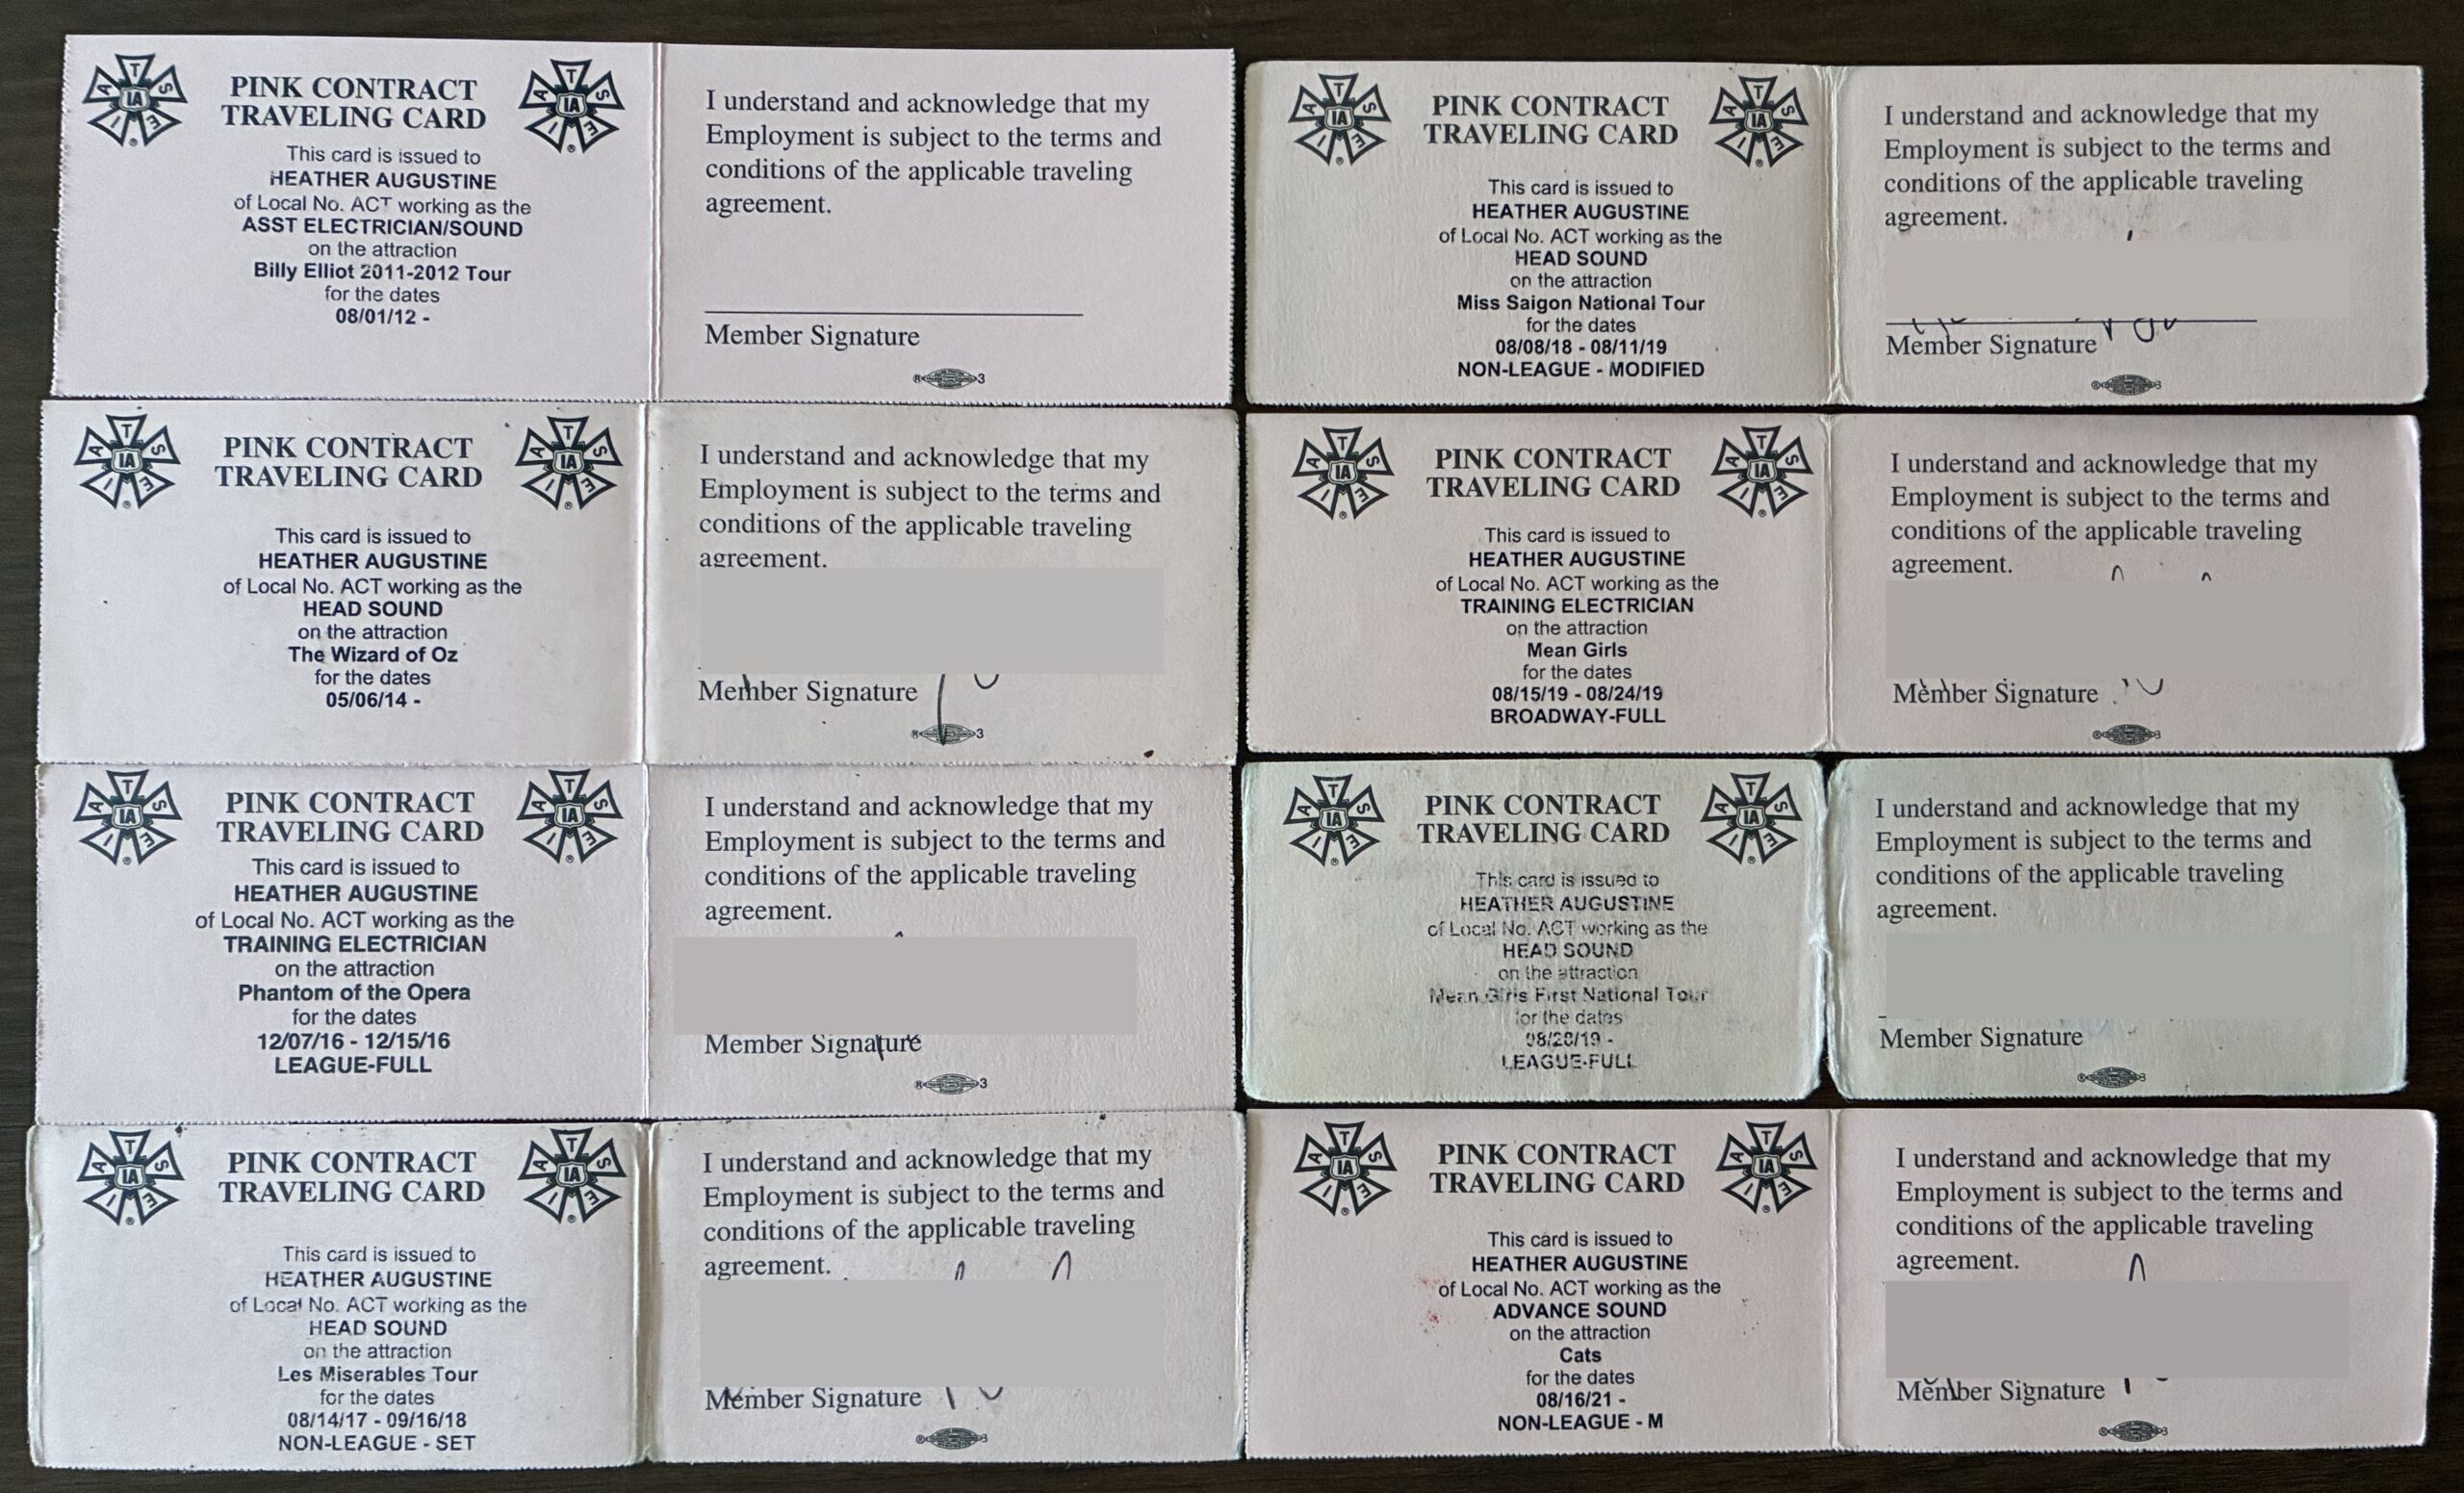
When you go on the road, you’ll have your membership card from IATSE showing you’ve paid your dues and are in good standing with the union and a contract (printed on pink cardstock, hence the name) with the show you’re on and the position you occupy.

Some companies are sending digital versions of the contracts, but I always had a physical copy which I kept in my wallet. You just have to make sure it’s somewhere accessible (i.e. not in a workbox on a truck that you won’t see until the end of load in), because there’s a tradition a lot of locals observe called “Cards and Contracts.”

At the first coffee break of load in the local steward will ask the road crew to show their signed and stamped IATSE membership cards and traveling card contracts.  Usually, this is an exchange, something like a show of union solidarity, you’ll give them your card and they give you theirs. Some theatres will have you sign a log book as well.

Stewards will give everyone a grace period at the beginning of the year as people are paying dues and the locals and the International are mailing out cards, but plan ahead.

Every once in a while you’ll get a steward who’s trying to test you. They’ll usually take your card, look at it, then ask if you have anything to ask them. If they do that, they just want you to ask for their card.

As an IATSE member, you have a contract negotiated for you with base salaries, rules for overtime and holiday pay, requirements for housing, and benefits that the employer is required to pay into. When contracts come up for renegotiation the union will typically ask the stewards to get their crew’s input on what the priorities are for negotiation and, once the two parties have ironed out the new terms, the membership will vote whether to ratify or reject the contract.

On each show, tour or Broadway, you’ll have a steward elected by the crew. This should be a person who understands the contract and is personable enough to have a conversation with management, but can hold their own if there’s an issue that needs to be resolved. It can be a thankless role, but it’s an important one. They’re the line of communication between the show crews and the International office if there are questions about how the company is interpreting the contract or workplace conditions.

Being a part of IATSE opens up a lot of opportunities depending on what you want to do in your career. It’s well worth looking into what your options are to join a local in your area or contact production managers if you’re interested in touring.

Our unions take care of us in many ways. Not only do they help negotiate fair working conditions, they also have programs for healthcare and retirement benefits. Over the next two blog posts I’ll talk about those benefits for pink contracts and some things you should know to navigate them.

Oh, $%*@&#!

I’ve had countless people ask me, “what’s the biggest mistake you’ve made?” Fortunately for me, most of my stories were smaller things that the audience might not have noticed or equipment malfunctions that I couldn’t control. That changed a couple months ago.

We all like to think that the longer we do something, the less likely we are to slip up. Practice makes perfect, right? The reality is, if you do anything enough times, even the one-in-a-million chance will happen. Sometimes it’s the equipment, other times it’s a slip up from inattention. No matter our best intentions, our jobs can be unpredictable.

In this case, it was human error. 

I was subbing on the mix at SIX, in the middle of the opening number, a little more on-alert than normal because we had a swing going on for the first time as Aragon. That in itself wasn’t too stressful; it mostly meant I was glancing over more often to check the chat on the RF computer, watching if the A1 (who was running the deck track) had any adjustments for the swing’s in-ears.

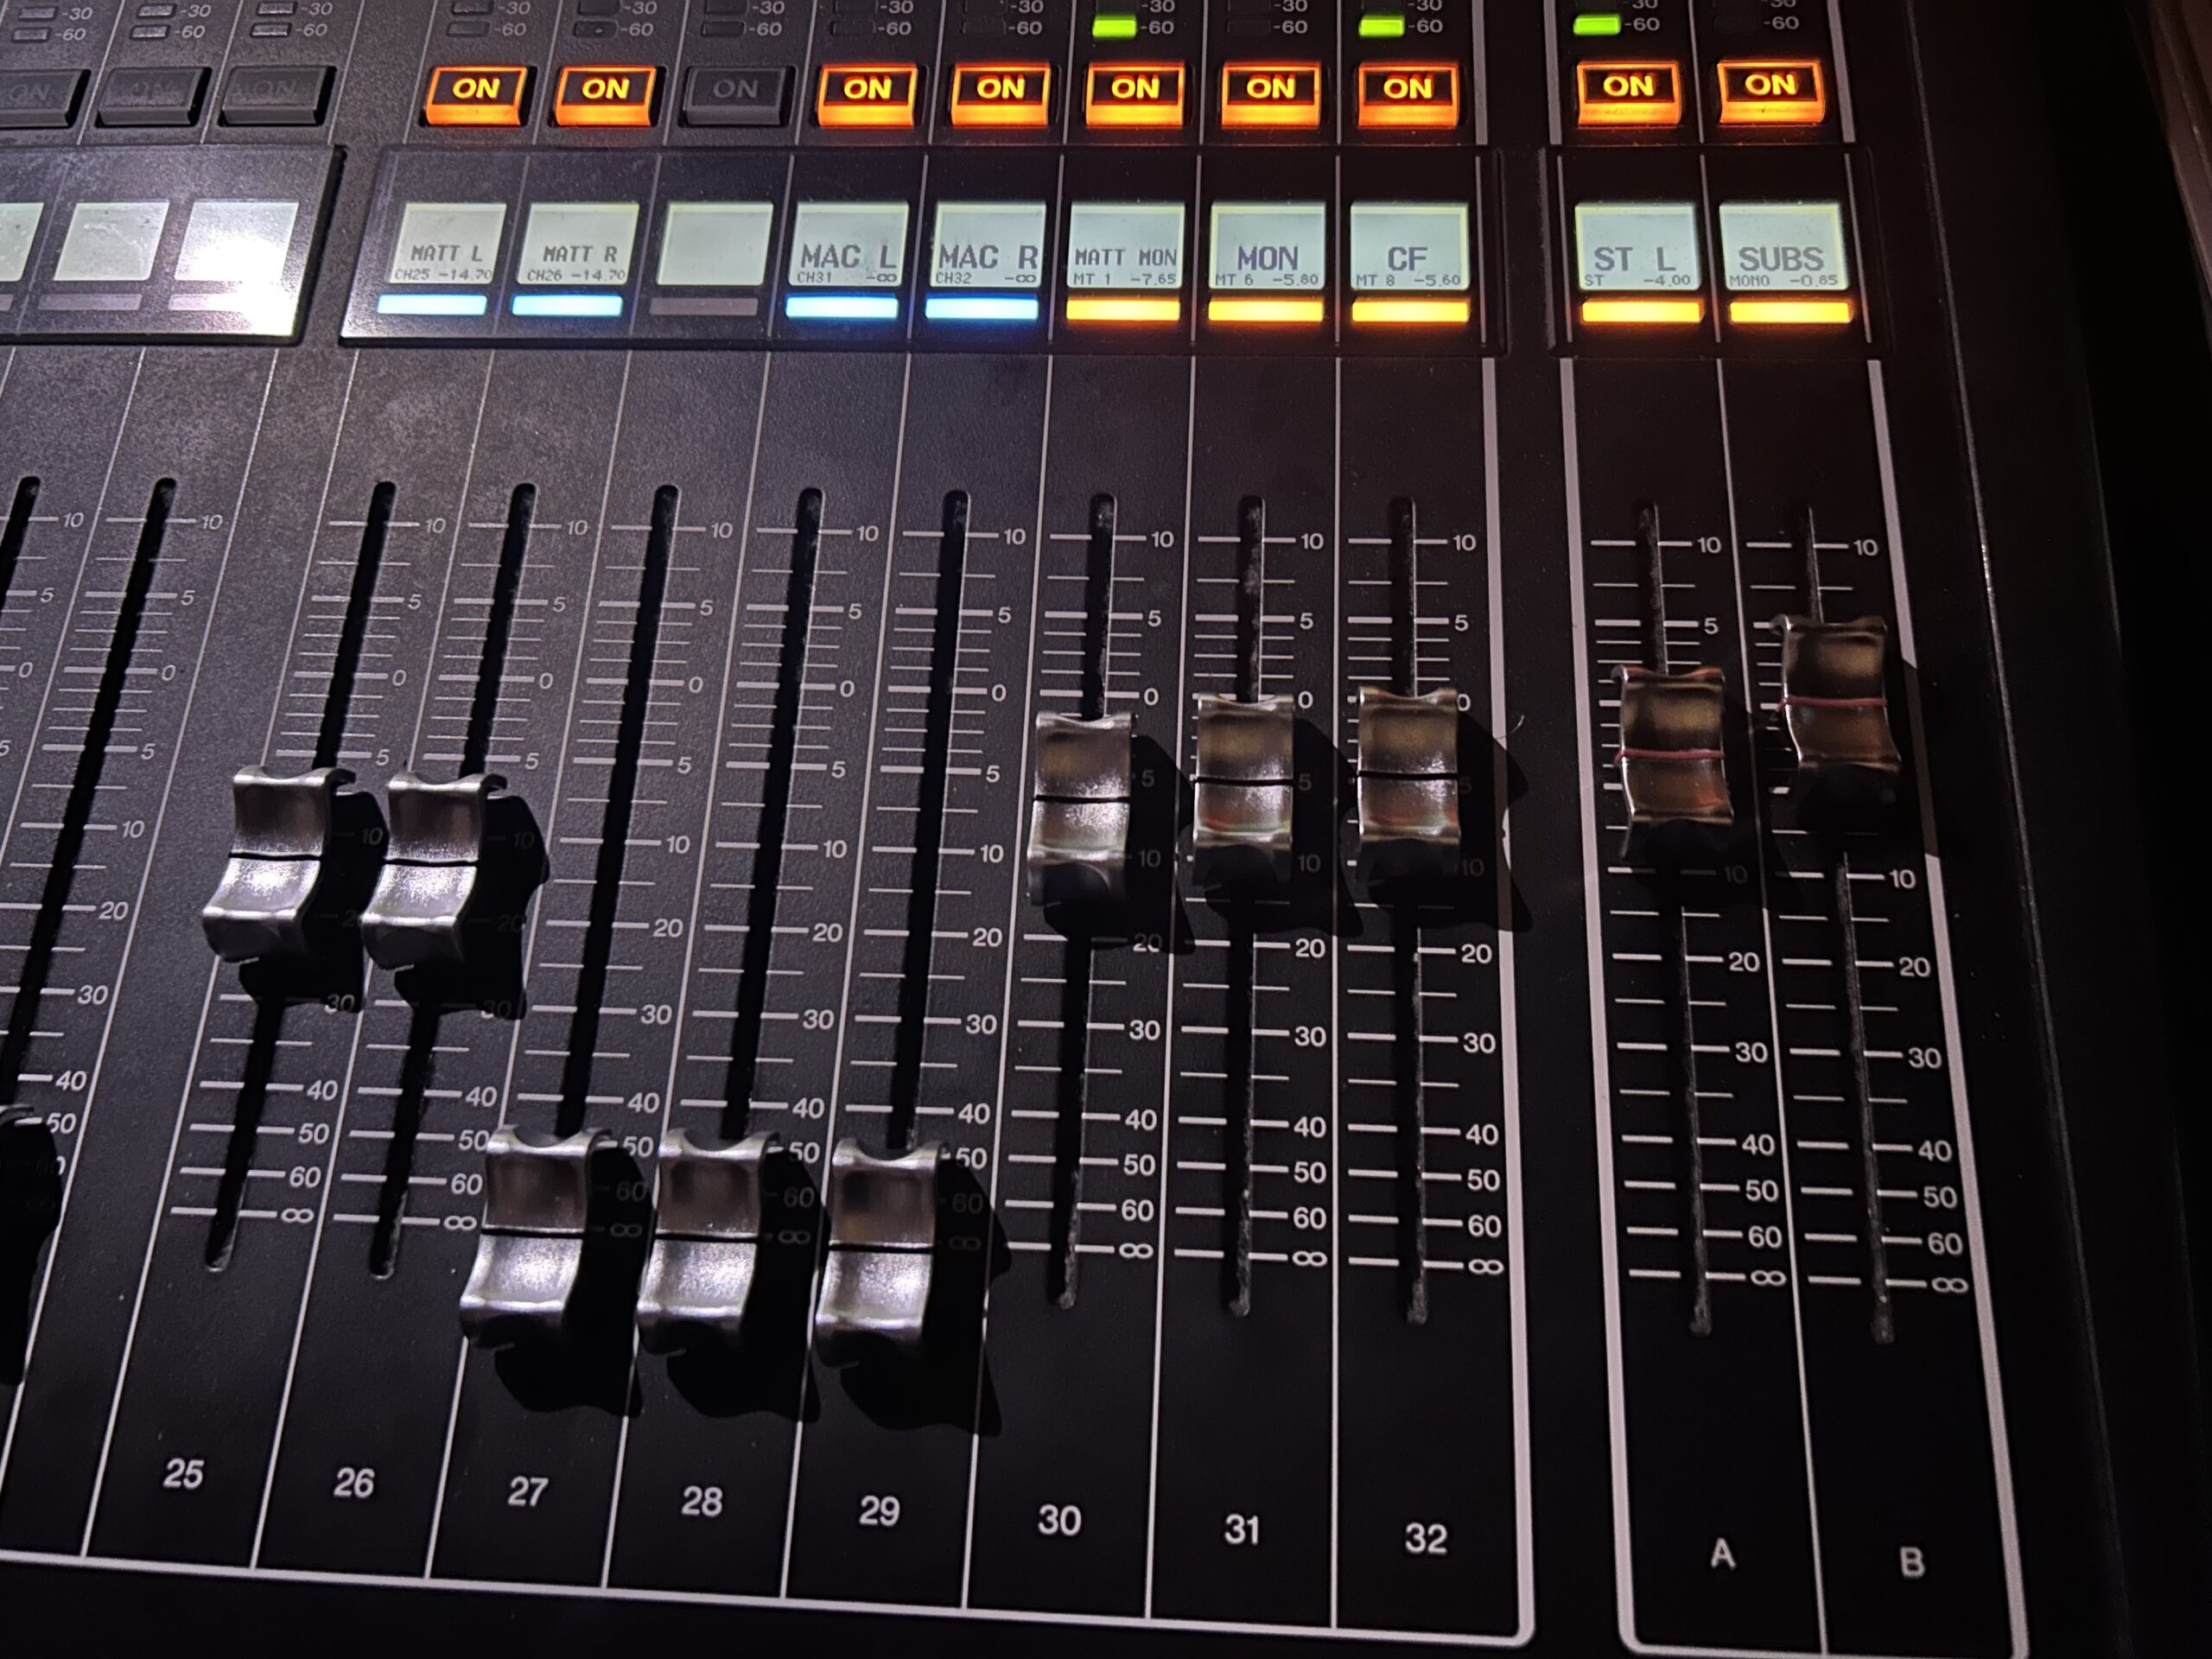
Everything was going well. The chat was quiet, the Queens were belting their hearts out, the band had just rocked their solos, and I hit their reset right on the beat, a simultaneous move of hitting a macro (a pre-programmable button) and popping their CG fader to the right mark (Control Groups on DiGiCo consoles, also called DCAs or VCAs on other boards).

We continued along and were about to head into the last big chorus of the song when I fired a cue—

And immediately lost all my vocals.

My stomach felt like it dropped to my toes and my censored thoughts would have made the strongest password in existence.

The band was (thankfully) still in the system and a panicked glance at the stage showed me that the Queens were still singing, but you couldn’t hear their un-amplified voices over the band.

Fighting through the initial panic, I looked down and saw I didn’t have any of the Queens on the CGs in front of me. Analysis mode kicked in and I knew that meant I was either in the wrong snapshot, or the data had been wiped from the one I was in (highly unlikely). However, likely or not, either problem would be fixed by firing the first snapshot of the opening number.

The vocals came back and I remembered how to breathe. 

Now we were functional, but I needed to get my show back on track.

First, I went to the cue list on the Qlab computer to line up where we needed to be. That’s when I saw that the playhead (which shows which cue will fire next) was all the way at the top when it should have been several cues down the list by this point in the show.

I’d found the culprit! Somehow the playhead had reset to the top and when I fired the next cue, it put us back into the preset snapshot, which only had the band on the CGs.

For context: British design teams typically use Qlab as the hub to fire everything (console snapshots, sound effects, reverbs, etc). American designers typically used the console as that main controller.

Even though I didn’t know why the playhead reset, I at least knew what caused the immediate problem. I radioed backstage to tell the A1 and let them know that Qlab had reset for some reason (what caused the chaos), I should be able to get back on track (no need for a show stop or other extreme measures), but I wasn’t sure why (some additional troubleshooting might be required).

As I was relaying that information, I looked back at the console and saw my macros.

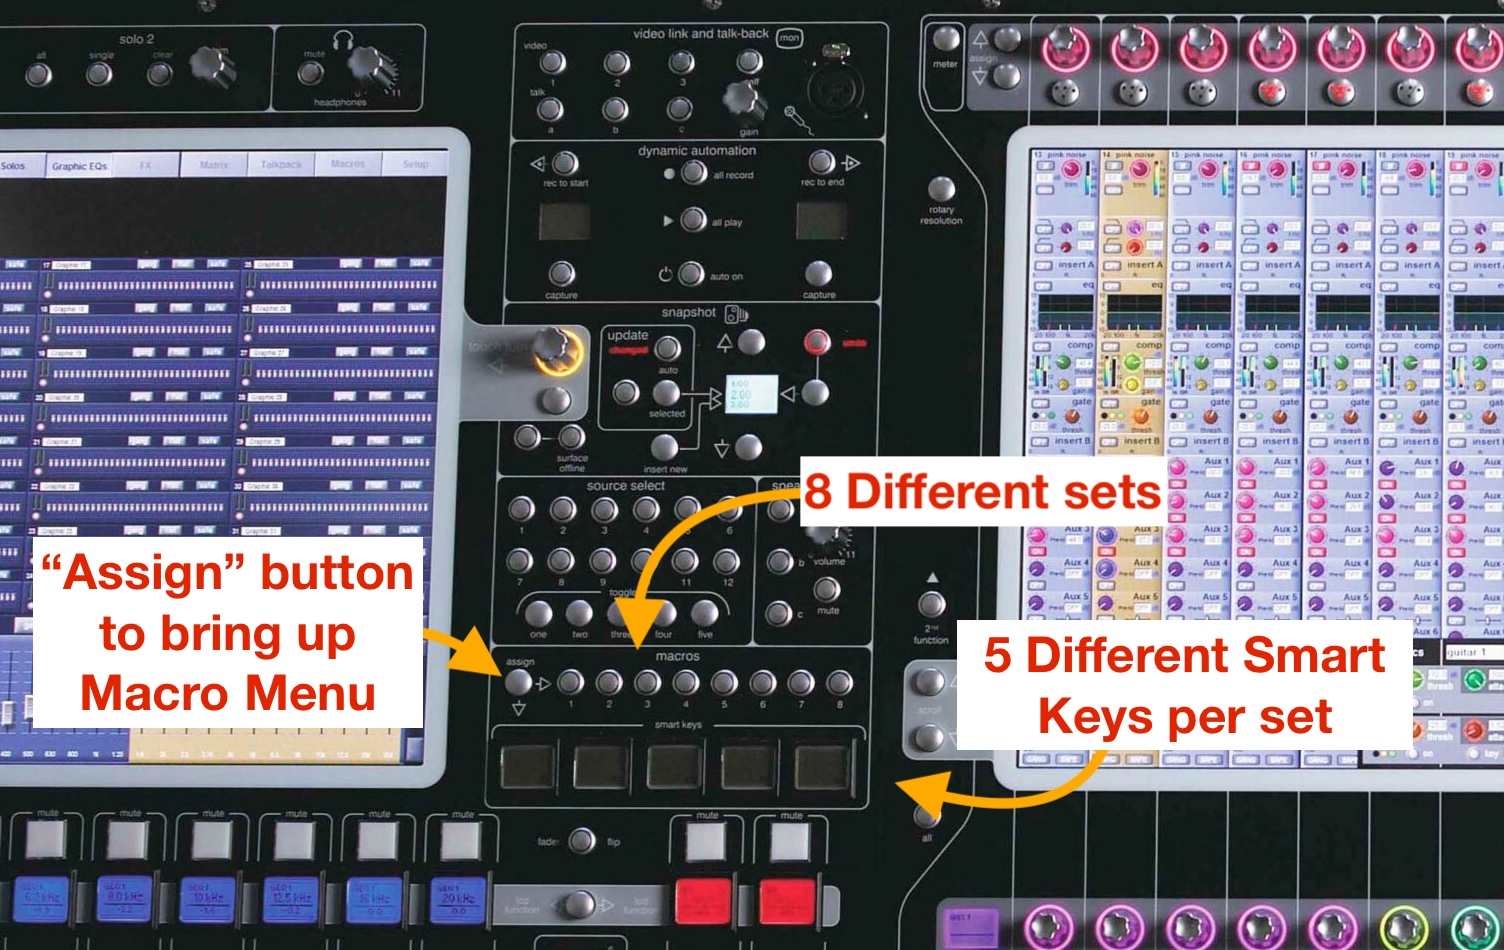
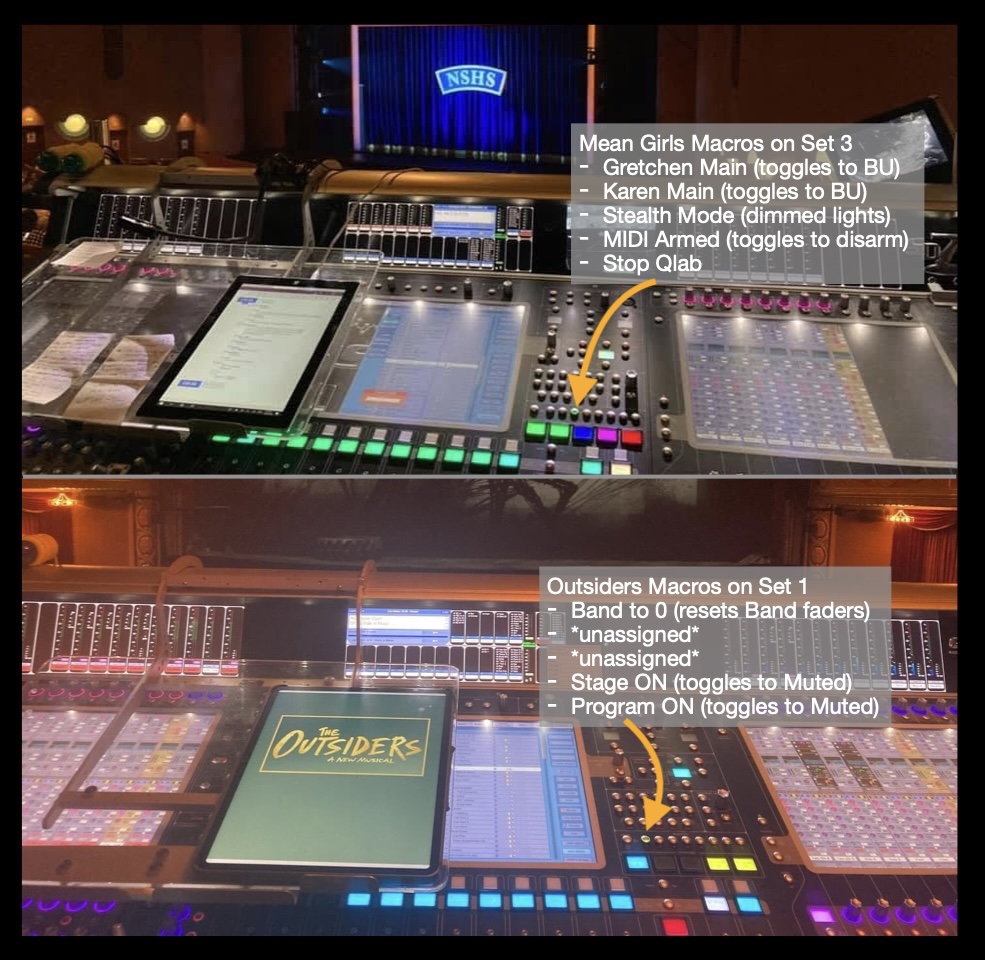
On the SD7 there are 5 physical buttons on the console and 8 different “sets” that you can select from, for a total of 40 macros that are quickly accessible. For SIX, if you’re on Set 2, you have triggers for Qlab: “Previous” or “Next” to move the playhead up or down the list, “Go” for firing the selected cue, “Stop All,” or “Reset All” which moves the playhead back to the top of the list.

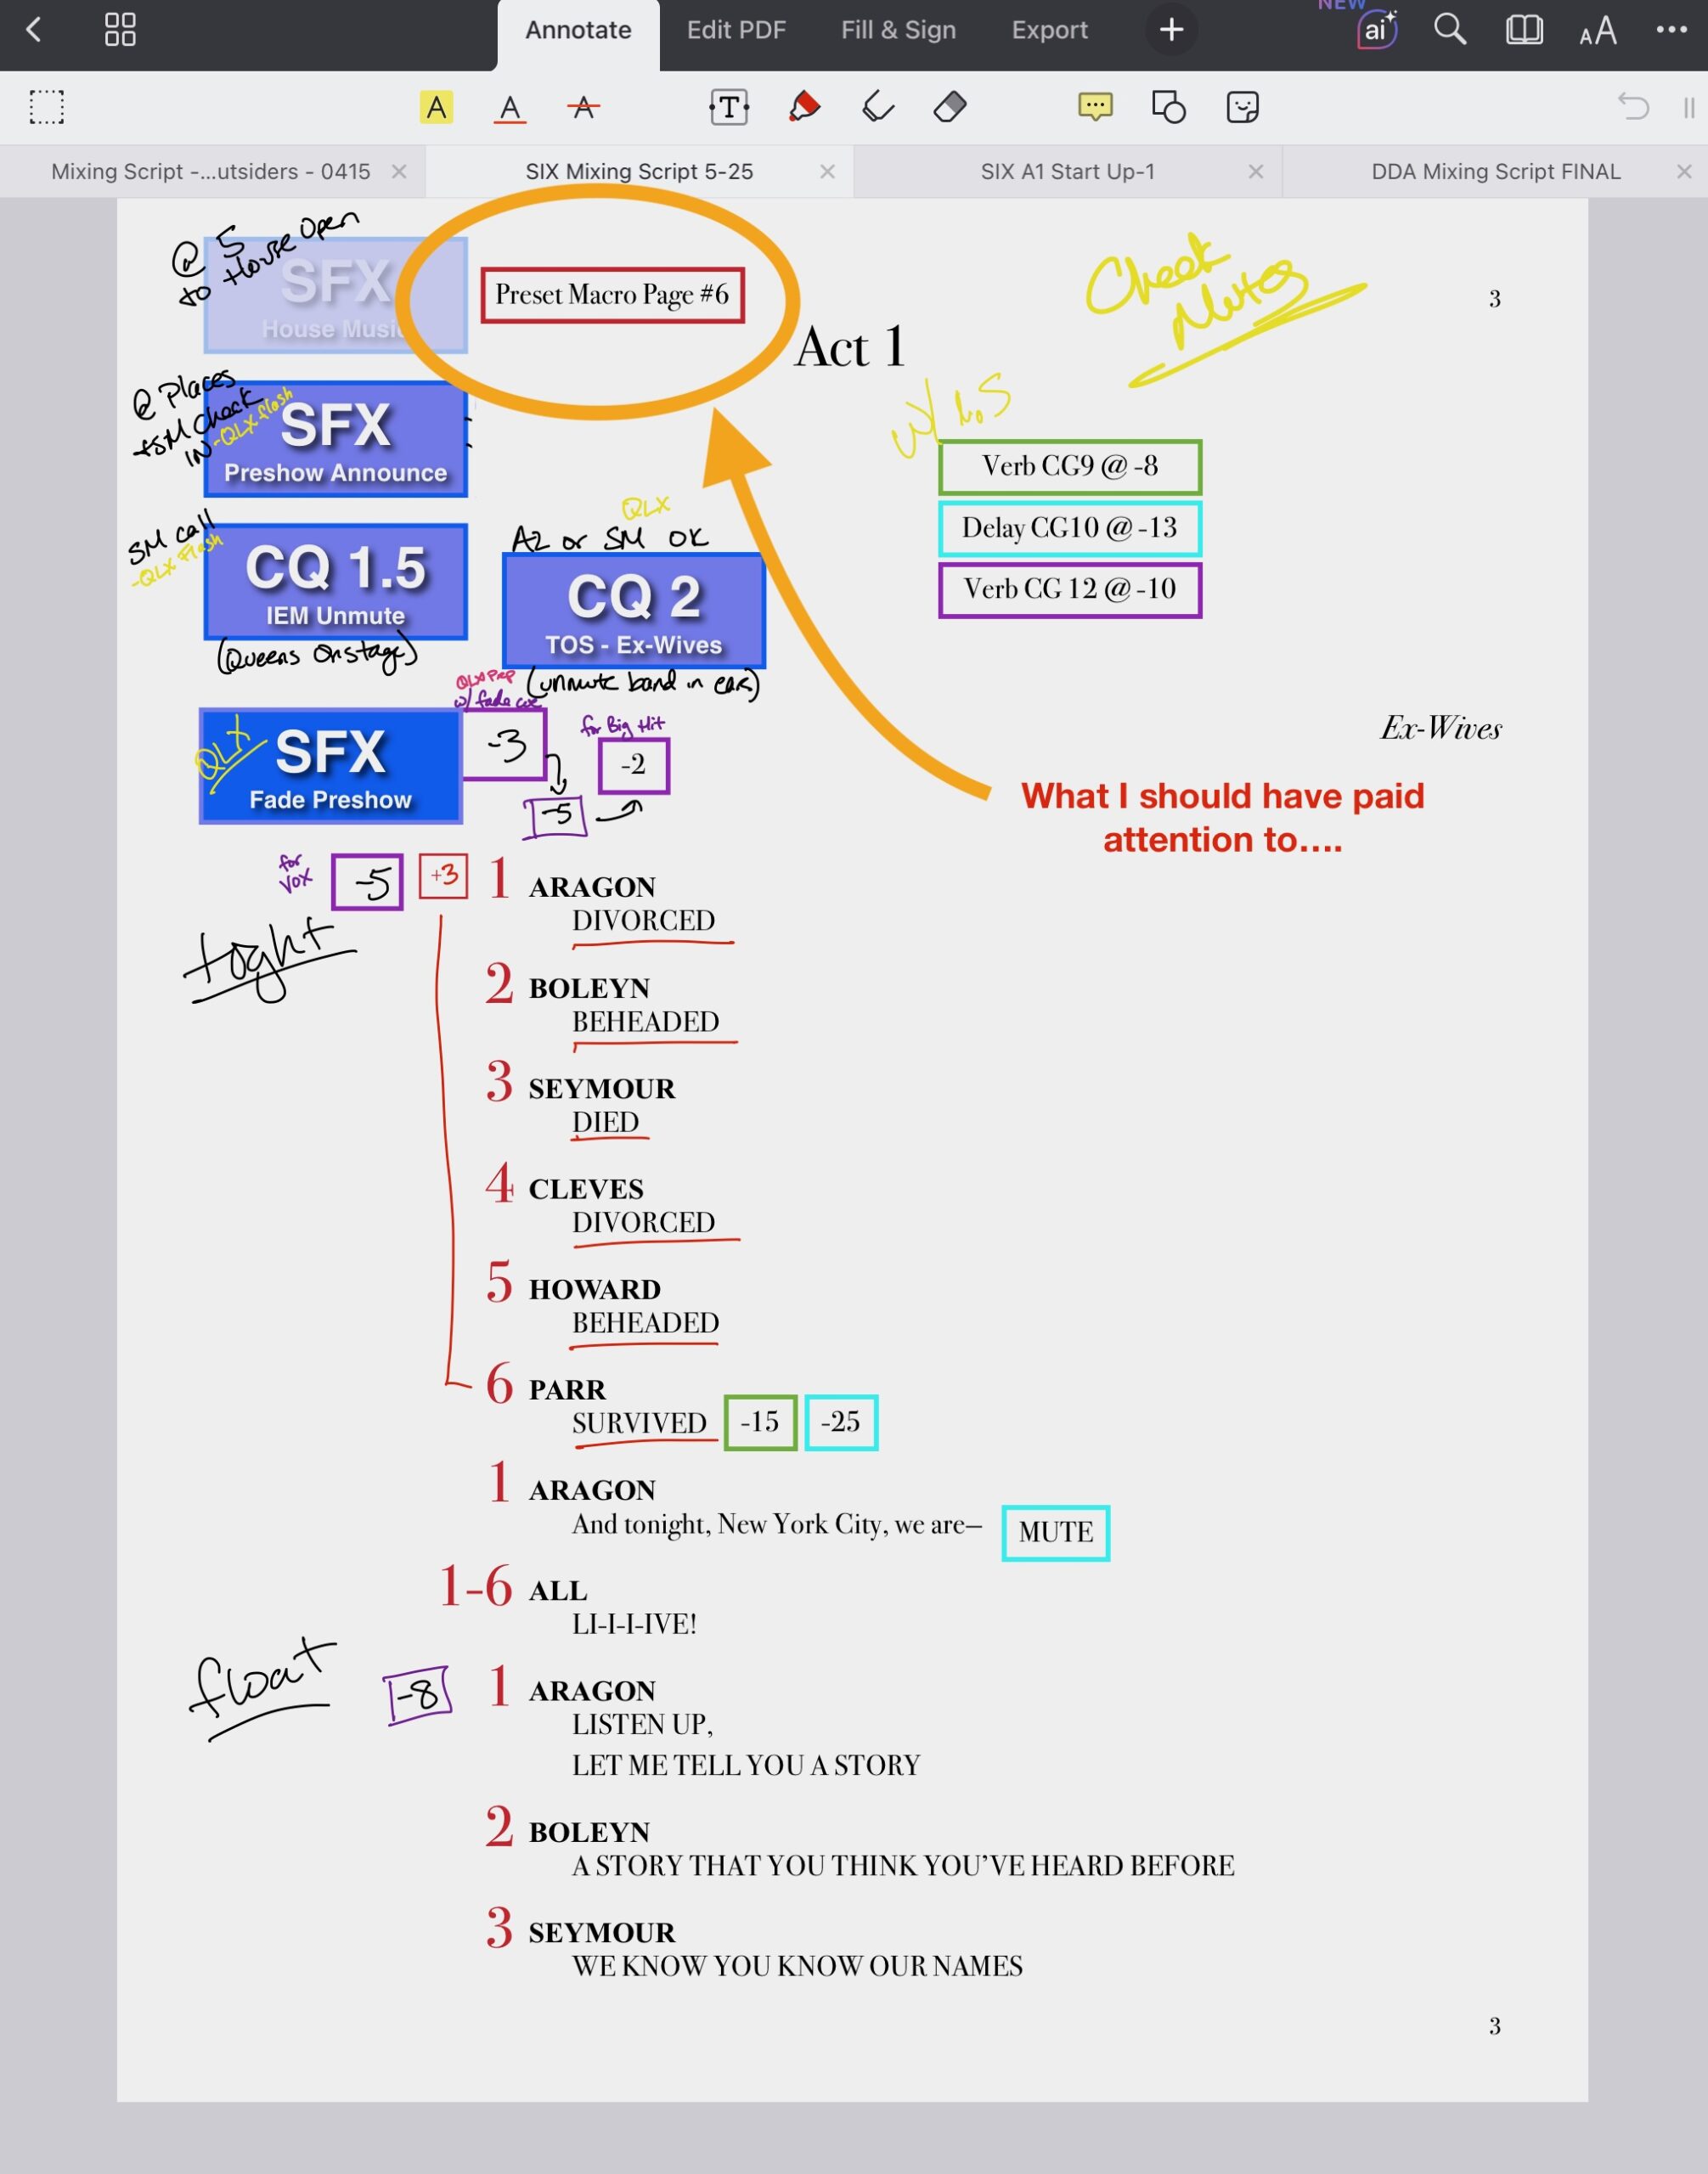
While you’re running the show, you want to be on Set 6. This set has a “Reset Band” macro that you use to re-racks the band faders to unity after you push them for solos. This band reset happens to be on the fifth button of that set….the same button that is “Reset All” on Set 2.

Everything clicked. We’d done a quick sound check with the new Aragon right before we opened the house and I’d reset the Qlab computers with the macros. Then completely ignored the note in my script to put the macros on Set 6.

Screenshot

That meant, instead of resetting the band CGs after their solos, I’d actually reset the playhead in Qlab, sending it back to the top of the playlist. When I fired my next cue, it triggered the preset snapshot instead, putting me in a cue without the Queens on my CGs.

Thankfully I can multitask, so I called myself a million types of an idiot while I used the “Next” Qlab macro to line up the right cue.

I had just enough time to take a deep breath, hit the band bump at the end of the song, and fire next cue which officially got me back on track. Once Aragon started her monologue I radioed backstage again to update the A1 on what I’d learned and let them know they didn’t need to troubleshoot anything.

All told, the whole event lasted maybe 30 seconds in total: 5 for the Queens to be out of the system and the rest to get back on track. But it felt like an eternity.

After the show, I promptly apologized to the A1 and described in detail what had happened. I knew that someone would have to tell Stage Management what to put in the performance report, so I offered to be the one to explain it. The A1 said they’d handle it.

I also apologized to the Queens as they were getting out of costume, especially the actress debuting as Aragon. If I hadn’t found her in the quick change booth, I would have gone to her dressing room to specifically check in about what had happened.

All in all, it wasn’t a great experience (it never is), but the fact that it was solved quickly and I took accountability immediately meant that everyone moved past the mistake with little fuss.

However, I took a little more time than everyone else to get over it. When something goes wrong there’s a trust that breaks and needs time to repair. If equipment malfunctions, you find yourself on edge, just waiting for something else to go wrong. With human error, I lose trust in myself. For the rest of that show (and several shows after) I was constantly double checking what I was doing: watching the Qlab screen as I took a cue, obsessively checking that the macro page was on the right set. It takes time, but eventually you rebuild that trust and can relax back into the mix.

In my experience, there are six phases that happen when I make a mistake:

First: Panic. 

Unfortunately, this is one thing you can’t control when you mess up. You just have to acknowledge it and try to move on to the next step as quickly as you can, which is:

Troubleshooting.

The faster “WTF?!” turns into “WTF is going on?” the better. Gather data (like the Queens are no longer on the DCAs) so you can figure out what specifically is wrong and you can continue to:

Your Immediate Action.

What stops the bleeding? You don’t have to get back on track right now, just fix your immediate problem. In my case, it was putting us in a scene, any scene, that had the Queens on the CGs. That way we only lost them for a couple seconds instead of the full time it took for me to figure out what was going on. Once you’re functional you can start:

Course Correction.

You’re past the current danger, which means you can take a moment to figure out where you are and where you need to be. How do you get back to the right scene, the right effects, or ready to fire the next sound effect, etc. Once you’re back on track you can:

Analyze. 

You’ve freed up more brain space and you can go through the problem, how you had to fix it, and make some logical conclusions about what happened.

Some of these steps happen simultaneously. You can panic while you troubleshoot. Course correction gives you information to analyze what went wrong, but not always the full picture. Sometimes you need help figuring things out which leads us to the last step:

Communication.

This is the final and most important step. Whenever you can, let someone backstage (most likely your A2) know what’s going on. If you couldn’t figure out what caused the problem, they can keep an eye on things to see if they can identify it. If you already know what happened, they can stand down and don’t have to spend the rest of the show on high alert. They can also let other people (like SMs) know what’s happening so everyone’s on the same page while you get back to focusing on the mix.

If you don’t have an A2, get on com and talk to SMs directly, whether that’s a quick “I figured it out, we’re good” or a “honestly, no idea what happened, I’ll let you know, but be prepared for some surprises.”

Not only should you communicate in the moment, but follow up afterwards as well. Either at intermission or the end of the show (whichever comes first, don’t get into a habit of putting this off!), talk to management and anyone directly effected by the issue. Explain what happened, what the next steps will look like (if it’s something you need to fix), and apologize if it was your error.

As the sub, I went to the full time crew (the A1) and also talked to Aragon. If I were the full time A1 I would have gone to the SM myself to tell them how to word it for the show report.

Taking accountability builds trust and helps to diffuse a situation before people get worried and agitated. Our Aragon felt better that someone explained what happened, and was happy to extend some grace for being kept in the loop. The A1 appreciated hearing quickly that they didn’t have to spend the entire show worrying about what else could go wrong.

I’ve had countless (thankfully less show-critical) mistakes where the fallout has been minimal because I speak up immediately if I know I’m at fault.

On one show, I left a god mic muted during a preview and (of course) that was a show we had technical issues and needed to stop, but our SM couldn’t talk to the audience because his mic wasn’t going through the system.

When I got on com and told him it was my fault, he went from frantic and angry to just amped up on adrenaline. He would have been completely justified to get mad at me, but once he knew what was going on he actually thanked me for letting him know before he mistakenly yelled at someone else.

During tech on a different show, I muted a Qlab channel as I was flipping through banks, and we didn’t have music as we worked through a transition. I realized what had happened and called it out on radio that it was my mistake. Later the programmer and I joked that you could see that designer was ready to jump down the programmer’s throat but immediately deflated to “oh, that’s okay. Are we good now?” when I took the blame.

I’ve found it’s one of my superpowers that people don’t tend to stay mad at me. In large part that’s because I step up and take accountability, then do my best to fix the problem. My designers and management can see I’m proactive and only make a mistake once, while my colleagues learn that I won’t throw them under the bus if I’m in the wrong. Plus, it’s really hard for someone to yell at you when you agree that it’s your fault and apologize.

Mistakes can and will happen no matter where you are in your career. It’s how you deal with them that shows your true professionalism.

We Need To Talk About Tech

Let’s talk about one of the most important weeks in a theatre worker’s schedule

Tech Week

This period of time has also been nicknamed Hell Week, which is one of the first things I discovered on my arrival into the drama school world. Doesn’t sound promising, does it? In fact, a quick look at the Wikipedia entry for ‘Technical week’ reveals this information, and there’s also a ‘Controversy’ section which tells you the following:

“…the common daily schedule during this week is the ‘10 out of 12’ schedule, in which the members of the production will be actively working for ten hours out of the twelve hour shifts.”

The sources cited here are referring to theatre in the United States, but it’s also a problem in the UK. As has been pointed out elsewhere, these are long enough days for actors, but designers and technicians are almost always expected to stay even later into the night. And, as I have learnt over the past year, this isn’t just the case in professional theatre. Students are also putting in extremely long shifts.

There have been times where I’ve arrived home 18 hours after leaving, had just enough time for a quick shower before going straight to bed, then up again after five or six hours of sleep to do it all over again. I’ve seen people wolf down snacks while operating a desk rather than take an hour-long lunch break because things were deemed to be running behind. I’ve been in situations where stomachs are rumbling and energy levels are low, only for “let’s power through” to be the message. I’ve also found that, during tech, it becomes almost impossible to cook proper meals due to lack of time and resources. If it can’t be reheated in a microwave, it’s not an option, and you might even find yourself living on takeaways for a week or two (which isn’t ideal health-wise).

This kind of relentless schedule obviously isn’t good for anyone. I’ve recently seen some articles pop up in theatre publications about the impact on parents and carers, which is clearly a really important issue, but these discussions seem to be centred on performers, directors and producers rather than including technicians. And I’ve seen almost nothing about disabled or neurodivergent backstage workers. There seems to be a general reluctance to acknowledge the presence of techs with disabilities, while at the same time talking about the importance of a diverse workforce. But if we really want to make sure everyone feels welcome in theatre, we have to start practicing what we preach, and taking care of the issues surrounding tech would be an excellent place to start.

I will be completely honest. As an autistic sound technician, I have felt isolated, frustrated and let down on quite a few occasions. I have felt like my needs are not accommodated, and worse, that they don’t matter. People might say, “That’s just what tech is like: deal with it.” And people have said that. They might think changing their minds at the last minute about what time we can all leave the building isn’t a big deal. But to someone like me, who has carefully structured their entire daily routine and meal choices around the information they’ve been given, it is a very big deal and can lead to dysregulation. When such things are happening over a sustained period of time, they can even lead to burnout (and did for me, after one particular show).

Boundaries are a big issue for a lot of us, and it can be incredibly challenging to speak up and say you don’t feel comfortable with something, especially when you’re new in the industry or feel like there’s no one who will back you up. In an industry where freelancing is the norm, it’s unfortunately all too common for people to be afraid of “rocking the boat” because they may lose out on work. The attitude is: “Well, if you won’t do it, then we’ll find someone who will.” But we will only be able to move away from such attitudes if more and more people speak out against them.

If there’s one phrase I’ve become tired of hearing, it’s: “That’s just the way things are done.” And more often than not, it’s been said about tech (often accompanied with a smile when bandying around terms like ‘Hell Week’). But it really doesn’t have to be that way. Hard work and productivity doesn’t — and shouldn’t — have to come at a cost to our physical and mental health.

My End of Year Show – Sweeney Todd

Earlier this year I wrote about my first experience of theatre sound design and mixing. Hard as it is to believe, my time as a student has come to an end and I’ve just finished my final show, Sweeney Todd.

We were divided into two groups and assigned roles on either Sweeney Todd or The Witches of Eastwick. This was dependent on the proposals we submitted, stating our case for wanting to work on a particular show. I chose Sweeney Todd partly because of my interest in the story and the period in which it’s set, but I also wanted to challenge myself as much as possible. Sondheim is known for his complex musical arrangements and the songs in Sweeney Todd are notoriously difficult to perform. While this made the prospect of mixing the show pretty daunting, it was a great opportunity to put everything I learned this year into practice.

In the rehearsal room, I began the process of mentally figuring out how to balance the vocals. There are a lot of overlapping parts, and in fact one of the most taxing moments of the show also ended up being my favourite: ‘Kiss Me (Part II)’, sung by Anthony, Johanna, Judge Turpin and the Beadle. There is so much going on at a fast pace, and you really have to concentrate hard to follow the script. With so many different words being sung at the same time, it’s also really important to make sure each individual character can be heard clearly and that no one is drowned out. In addition, our production had only one male cast member, which meant finding the right balance between three female voices and one male voice (when originally this song would have been sung by three male voices and one female). All of this meant that, when it went right, it was immensely satisfying.

One of the other things that really appealed to me about Sweeney Todd was the news that our musical director would be using an amazing piece of orchestral software called Sinfonia. This allowed him to essentially be a one-man band while conducting the cast, and it was incredible to watch and to mix. It was certainly a challenge I embraced, as I had worked with tracks in QLab on my previous two shows, so it was good to have a different experience.

Another element I really enjoyed was using reverb. I’d done some research on past productions and was fascinated by how Broadway sound designer Nevin Steinberg used reverb creatively. While we obviously didn’t copy this approach, it did give us a few ideas. Our director encouraged us to have fun with reverb for the screams in the more violent scenes, and that’s exactly what we did. One particular scene involving a character being thrown into an oven was really exciting because everything came together so well: the reverb, the lighting and silhouette, the tension in the musical underscore.

That’s ultimately what I’ve loved most about mixing shows this year: the teamwork involved in bringing everything together and creating something that audiences walk out of saying, “That was brilliant.” Of course there were the usual technical difficulties and stresses, but the final show couldn’t have gone better. It was a sell-out audience, my family were there (the first time they’d ever seen one of my shows, which was really special) and everything sounded great and ran unbelievably smoothly (rare but wonderful!). It was an experience I’ll remember for a long time to come.

Save Early, Save Often

If you’ve been reading my blogs for a while, you’ve probably noticed that a lot of them don’t directly relate to sound. That’s because sound is actually such a small part of what we do on a day to day basis. Being an incredible mixer is all well and good, but if you crumble under pressure or can’t show up on time, you won’t work for long. If you’re an A2 or monitor engineer and you can’t communicate with people, you won’t even know what people need so you can effectively do your job.

Today I’m going to wander well off the sound waves into what I consider one of the most all encompassing topics for dealing with life: Money.

Now, I’ve been writing blogs for five years at this point. I can’t tell you how many drafts of this very topic I’ve written and hated. Money is such a taboo topic that we probably know more about our best friend’s sex life than we do about their bank account, so it hasn’t been easy trying to find the best way to talk about it. However, I’ve never been known for my subtlety, so we’re just going to dive in head first.

Money is important. We can go through all the overused sayings that money can’t buy happiness and that it isn’t everything, but the fact remains that money is a major factor in our lives. Having a savings account with a few months of expenses tucked away can make all the difference when emergencies or life changes come your way.

We all have different relationships with money. Part of it is nurture: the environment we grew up in and how we saw our parents handle money, but just as important is nature: who we are and what we value in our lives. My parents taught my sister and me similar things about money, but we have different priorities and habits that have developed because we’re different people with different life experiences in different careers.

This blog won’t have all the answers for every situation, but what I really want it to do is put financial literacy on your radar and maybe show what it can do for you, given time. That way you can start to figure out how you personally relate to money and what your priorities are.

Because time is your greatest asset. Even if you start small it can make a huge difference.

So, money is important, we get that. Where do we start?

First, start to pay attention to your money. Do you know roughly how much you make in a year? Do you know how much you spend? That’s the basis of all personal finance. You don’t have to go full forensic accountant on your life, but check your bank and credit card statements and start to see what your big picture is.

Personally, I don’t have a strict budget of “I can spend $X on groceries, $Y on clothing, and $Z on social activities,” but I do track my expenses, so I know roughly what I spend in a month or over a year. I use Quicken (any similar personal finance software will do a similar thing) which imports my transaction, lets me put them into categories, and I can generate a report if I want to check on things. You can also just use a spreadsheet: it can be a basic accounting tool, or you can go nuts with formulas and formatting if you really want to go in-depth and customize.

Once you’ve taken a look at that, you’ve found your baseline and rough expectations. Do you have extra money some months that you might be able to start saving? Does your income vary wildly each month so you need to put some into savings for your slow season? (Welcome to being a freelancer. By nature of our schedules, we have to be more financially aware than our 9 to 5 counterparts.)

Did you learn that you’ve been spending more than you make and your credit cards have made up the difference? Or that you’re making just enough and working paycheck to paycheck, but if anything out of the ordinary happens you’re operating on a razor thin margin?

If you’ve hit this point and you’re looking at things thinking, “oh shit!” take a moment and breathe. It’s okay. That feeling just means you have a goal to work towards.

Now that you know where you are, it’s time to look at where you want to be. Ideally you want to have minimal debt and be making more than you spend so you’re able to save. This process looks different for everyone, and Paula Pant, who runs the site Afford Anything, covers it more completely than I can in her post about “Growing the Gap.”

TLDR: you can try to grow your income (asking for a raise, monetizing a side hustle, investing, etc) while keeping your spending the same, or decreasing your spending while you income stays consistent. Doing either of those create a “gap” between what you make and what you spend, so you’re able to put that into paying off debt, savings, or eventually investing.

Once you can start saving, your money will start to work for you. Which is a concept that’s difficult to really understand until you’ve seen it in action. You may have heard the term “compounding interest” bandied about like some magic phrase, but what does that actually look like?

It means a savings account will pay you interest, and that interest will keep adding up.

It means a business can make a profit, which you can put back into it to make it bigger and more productive.

It means a stock might pay you a dividend which can be reinvested, adding more shares to your portfolio.

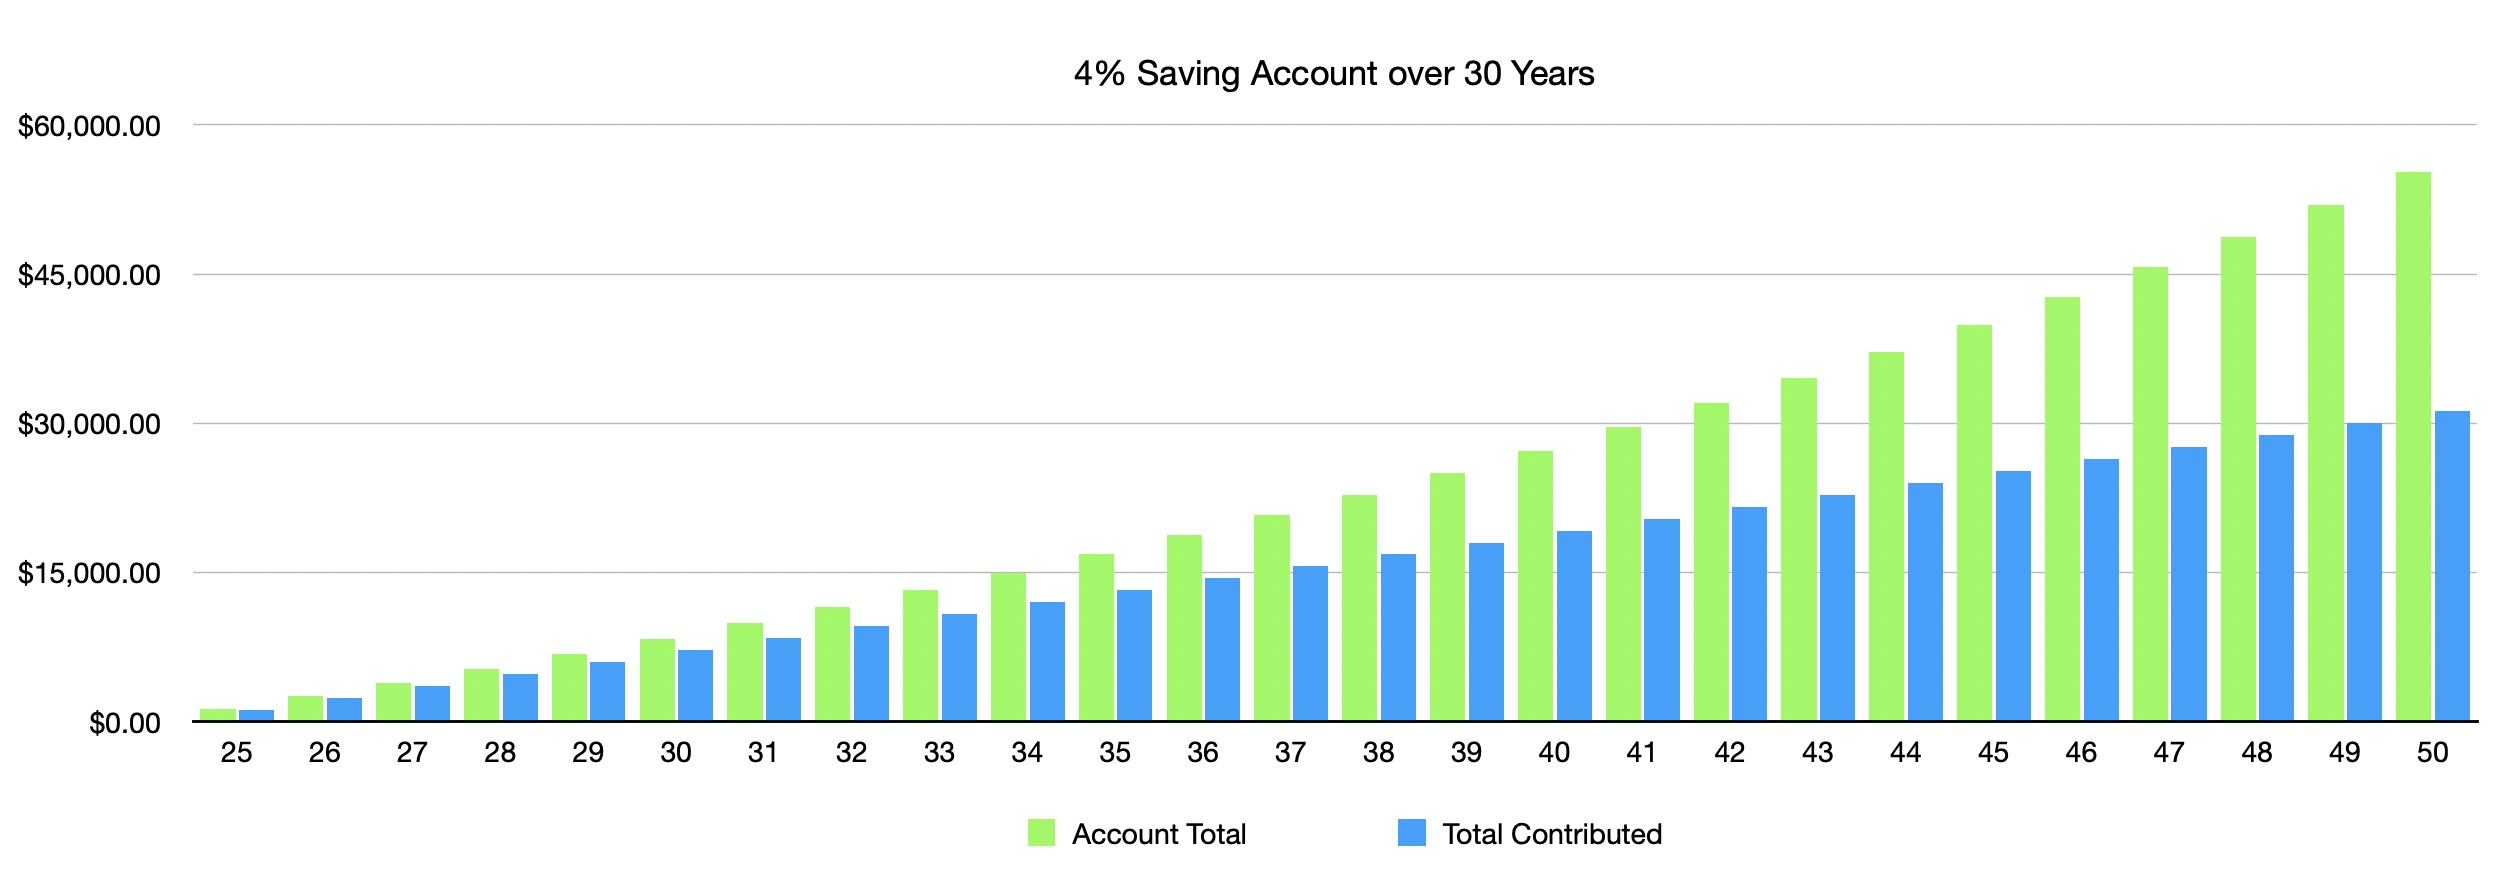
Let’s look at an example savings account. A high-yield one might pay 4% interest per year:

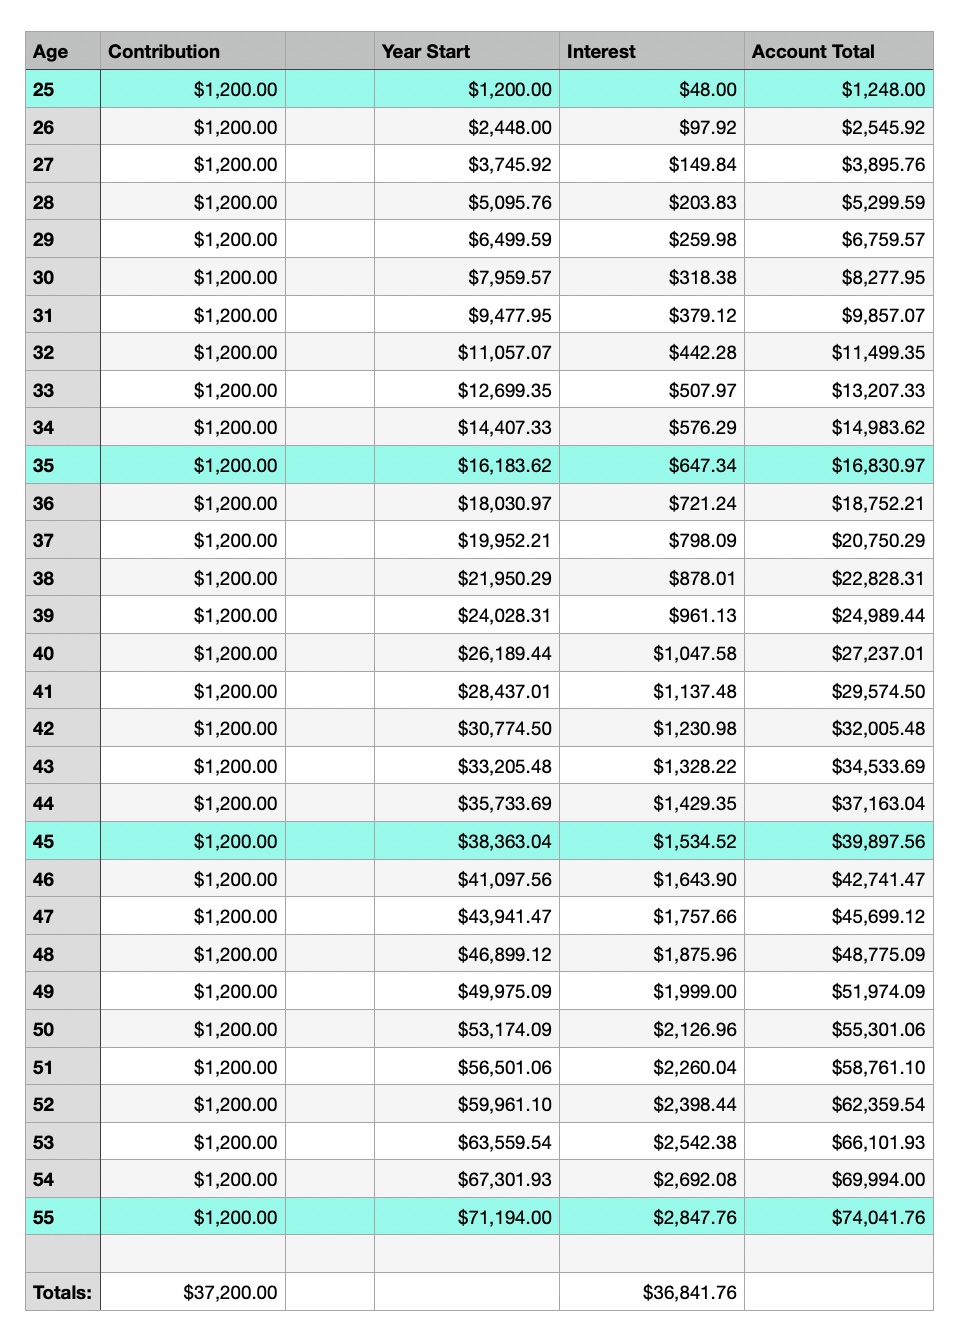
At 25 years old, you put in $100 a month. At 55 years old, you would have put in $37,000 ($1,200 per year for 30 years), but the account balance would actually be $74,000. It’s double what you put in it, but where did the other $37,000 come from?

The interest.

So the first year you put in $1,200. The interest on that was $48.

Total of $1,248.

The next year you add $1,200, now the balance is $2,448, and interest on that is $97.

Total: $2,545.

Next year is another $1,200, the balance is $3,745, and interest on that is $149.

Total: $3,895.

Screenshot


And so it continues with the interest getting just a little bit bigger year after year.

At 35 you’ve put in $13,000 and the account would be $16,000.

At 45 you’ve put in $25,000 and the account would be almost $40,000.

Time is the magic ingredient in a lot of financial success. If you give it some training (invest it, put it in savings, start a business, etc), soon it’ll start working all on its own.

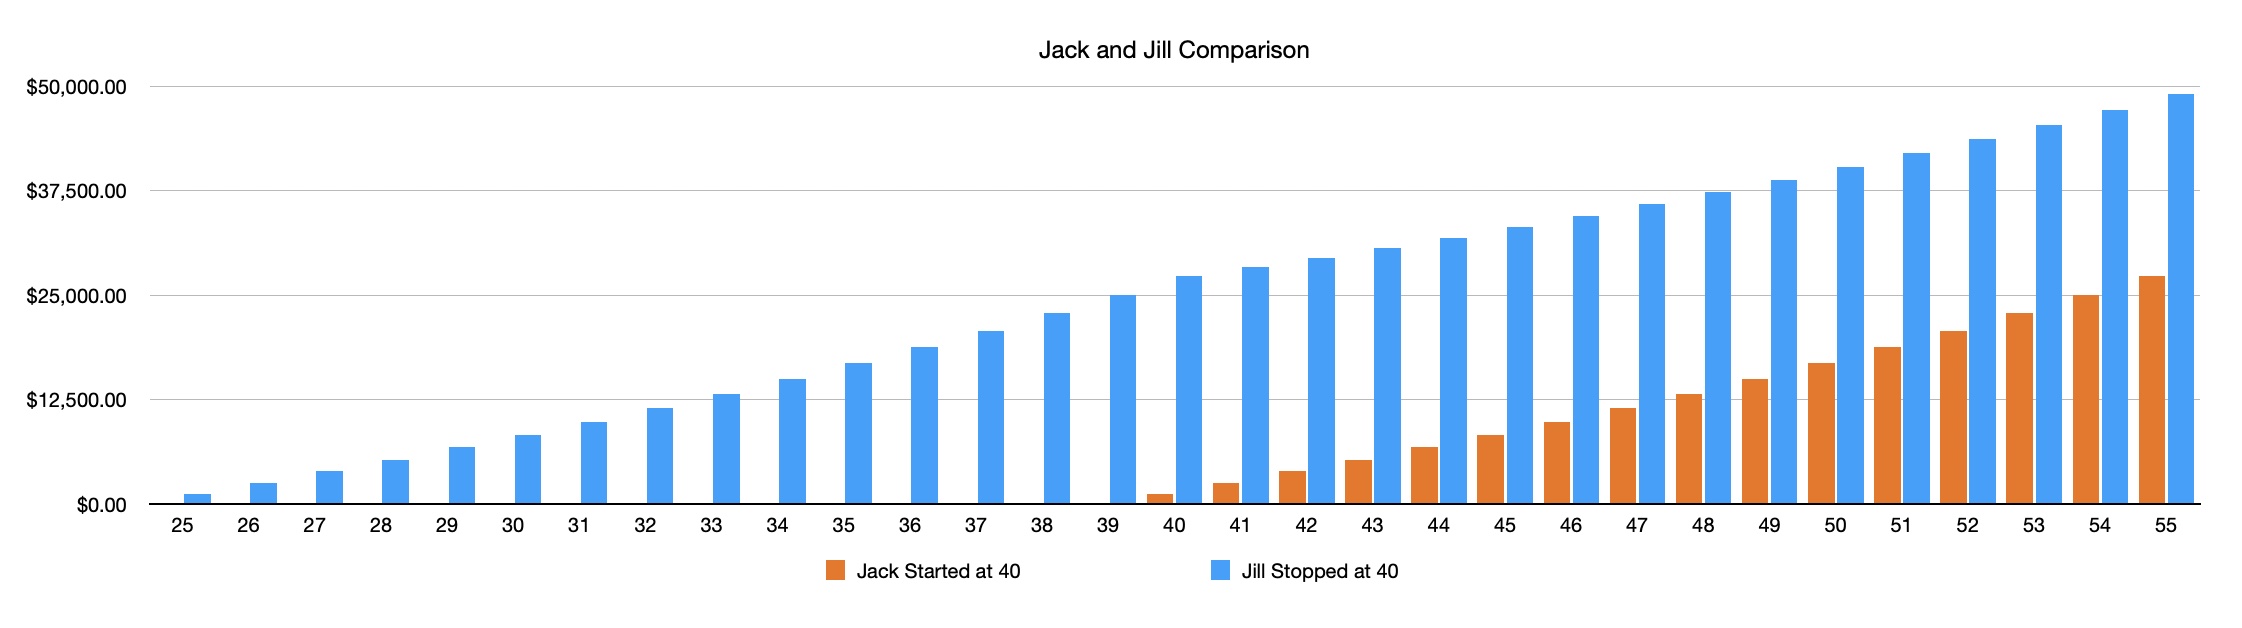
One of the favorite financial tools to illustrate the benefit of compounding interest is called the “Jack and Jill” comparison. It looks at Jill, someone who started saving/investing at the beginning of her career, and Jack, who decided to wait a few years.

Let’s look at this in a couple different scenarios:

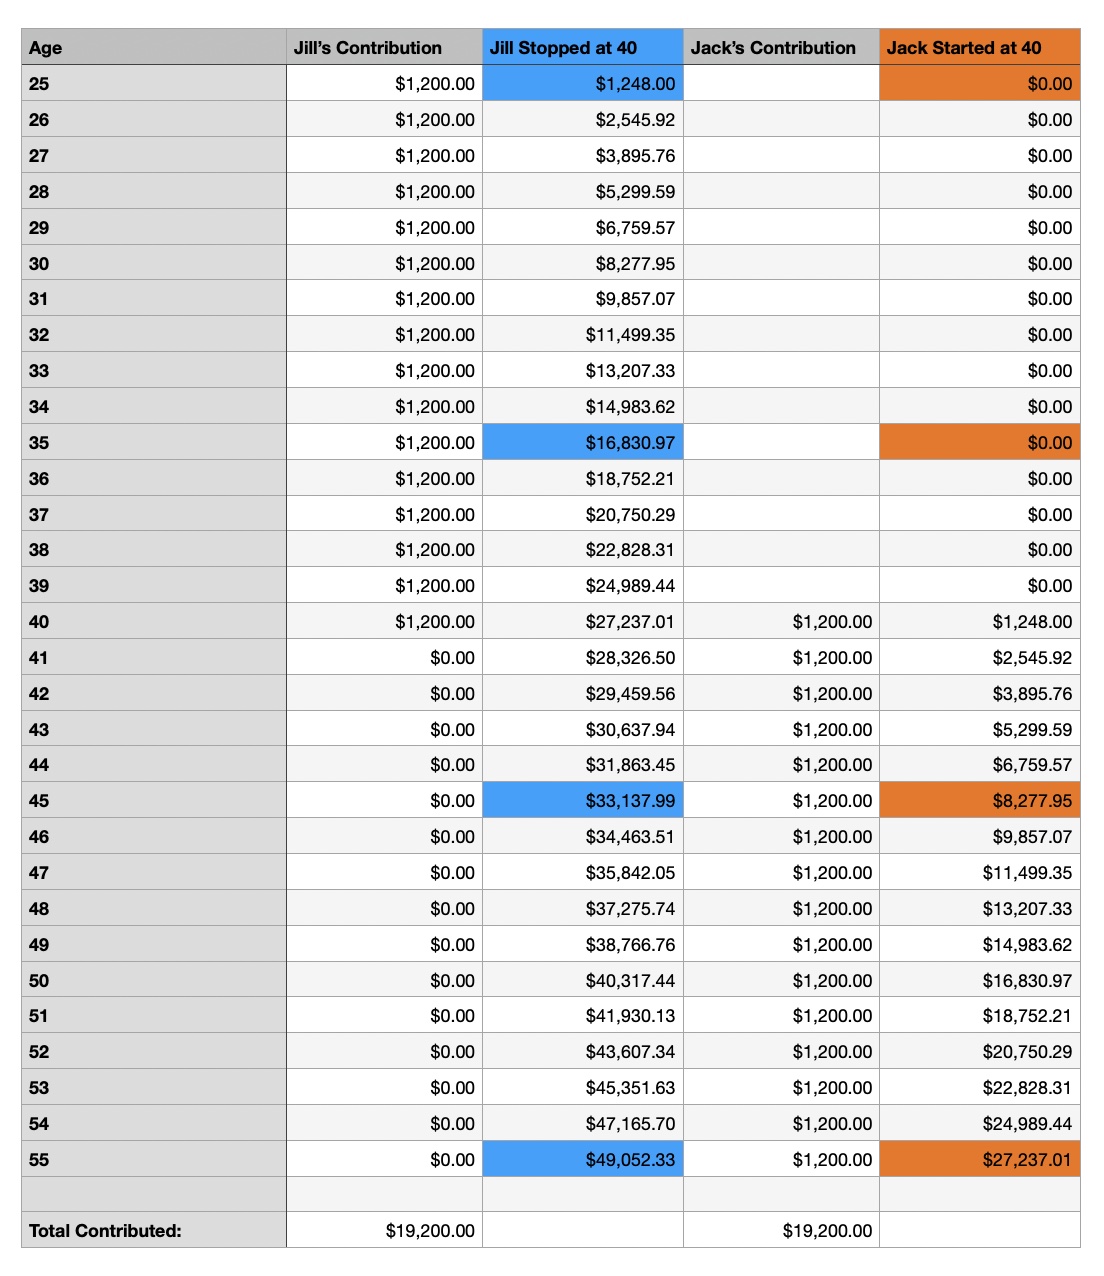
First: Jill starts investing $1,200 per year when she’s 25, stops when she’s 40, and just lets the account grow on its own from there.

Jack starts investing $1,200 per year at 40, until he’s 55.

Screenshot

Both contributed the same amount: $19,200. But when they’re both 55 Jill’s account is almost $50,000, while Jack’s is only $27,000. Those extra 15 years of interest make a $23,000 difference for Jill.

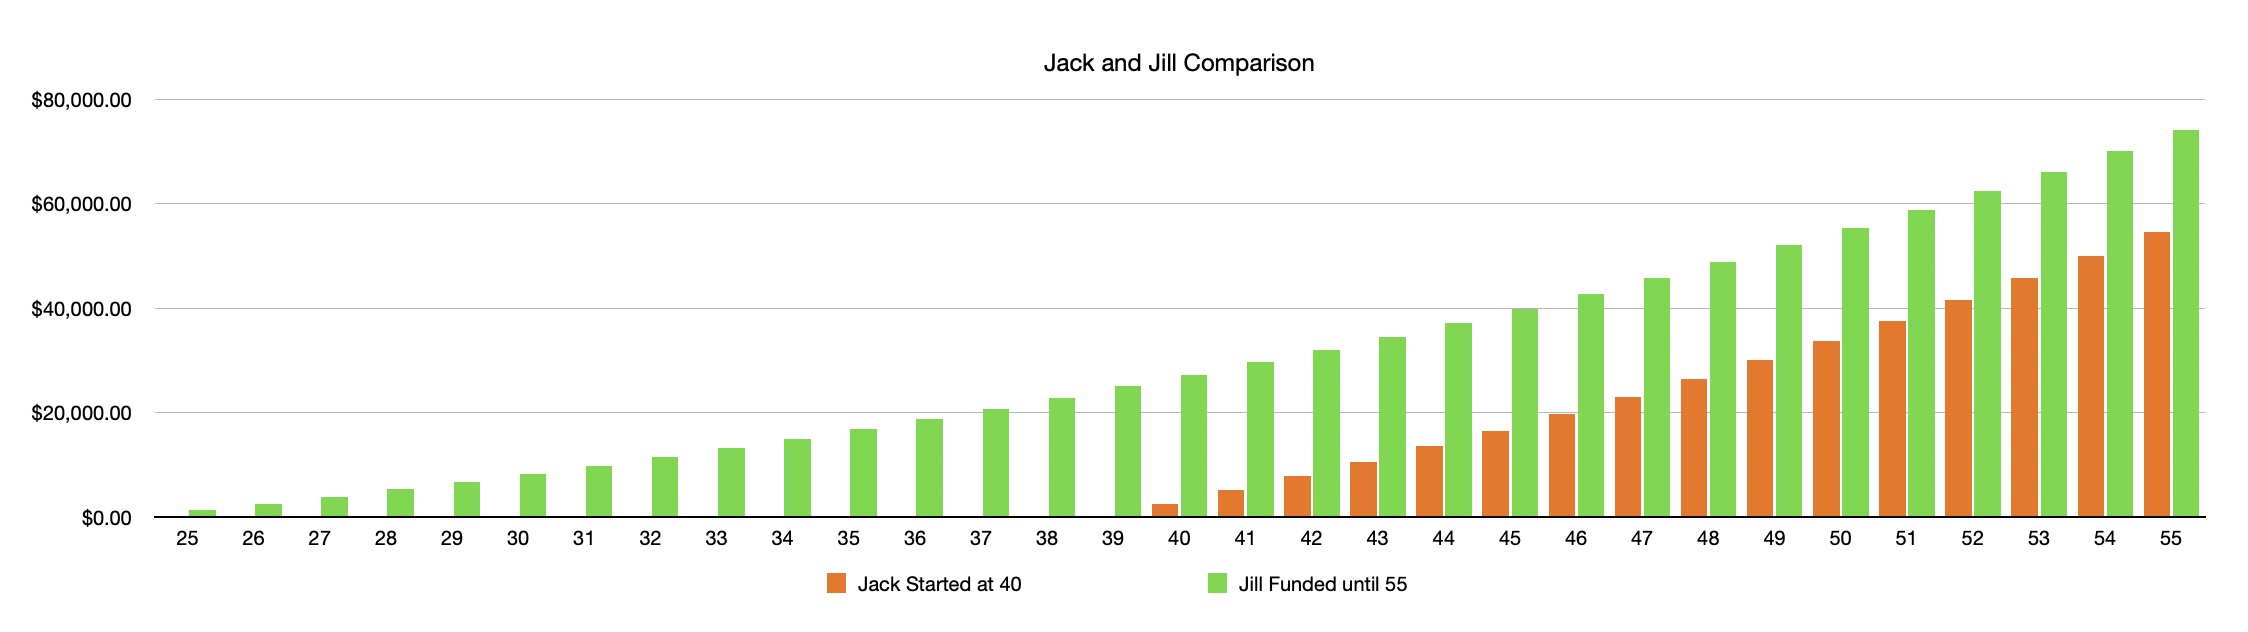
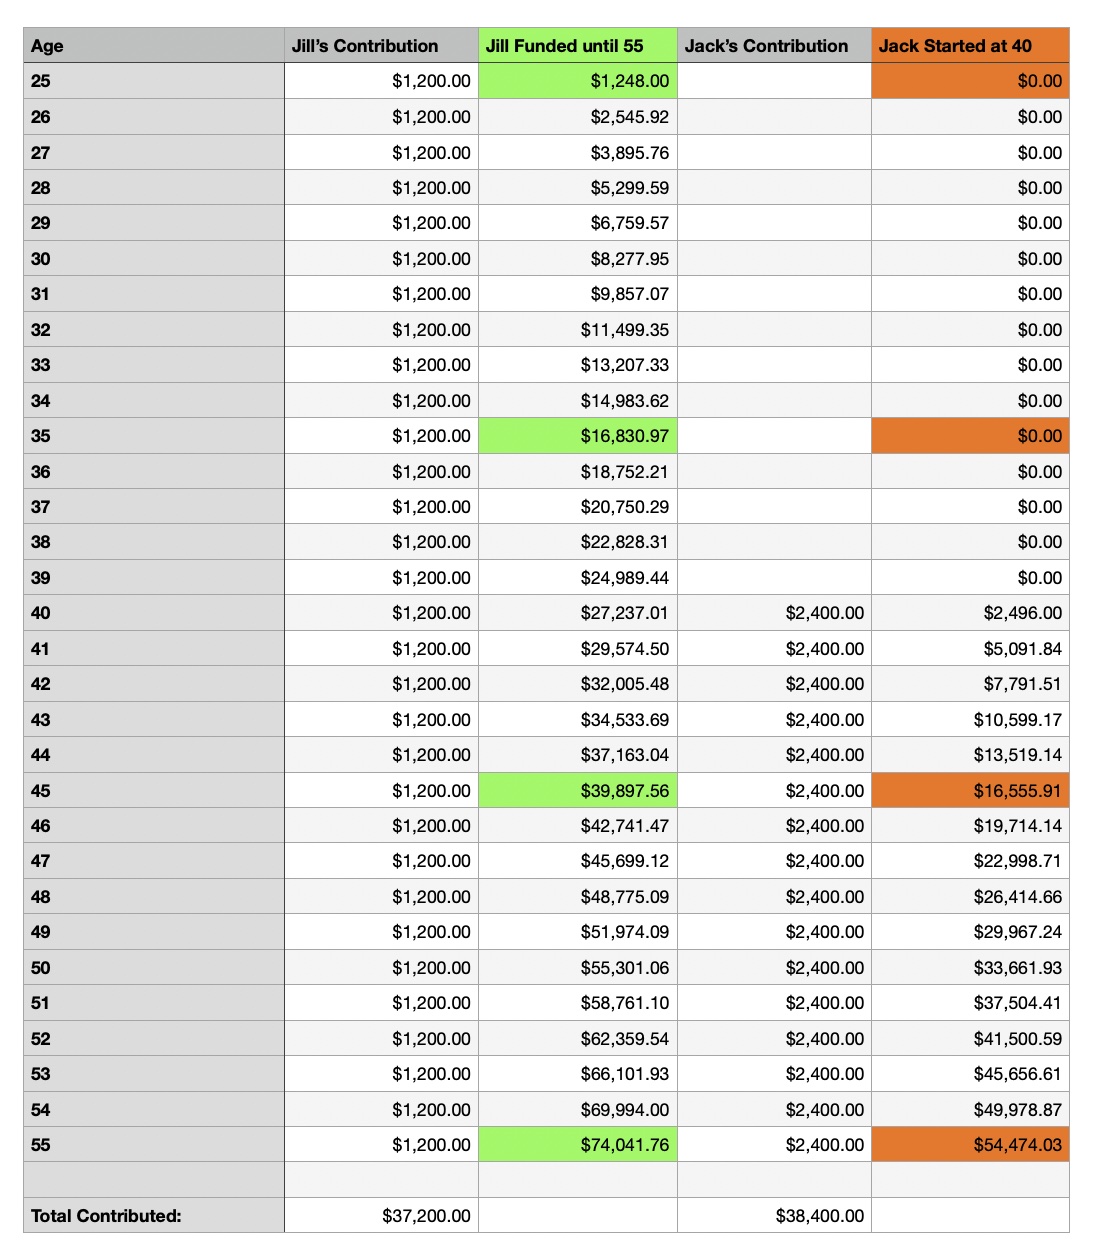
In another situation, Jill starts investing $1,200 per year when she’s 25 and keeps going until she’s 55.

Jack starts investing at 40, but he puts in $2,400 per year so he can catch up.

Jack actually ends up contributing at little bit more than Jill: his $38,400 to her $37,200.

Her account is still ends up being $20,000 more than his: hers is $74,000 to his $54,000.

The moral of the story? Start early. Time is your friend, not only in compounding interest, but the sooner you start paying attention to your money, the more you learn and the better you get at managing it.

There’s a proverb that says “The best time to plant a tree was 20 years ago. The second best time is now.” Since most of the readers of this blog are fairly early in your careers, my hope is that in 20 years you can look back at this “tree” and be happy you planted it when you did.

Hypothetical scenarios are all well and good, but how do you start digging?

If you’re just starting out and all this feels completely overwhelming, take a look at Dave Ramsey’s Baby Steps. He’s built an empire around financial literacy, but I recommend you treat it as a good place to get your bearings, but not the gospel truth. Steps 1-3 are a good place to start and once those make sense, look around at other philosophies (like the ones below). I don’t agree with everything he recommends (doing away with credit cards and investing in mutual funds being the main points of contention), but his method can be a helpful resource to get yourself started.

For anyone who feels financially stable but doesn’t know the first thing about investing, take a look at JL Collin’s blog. He does a good job of talking about the stock market in accessible terms and is a proponent of simple, set-it-and-forget-it investing. (He also has a book that I highly recommend.) Paula Pant, who I mentioned early, is at Afford Anything, and offers another take on managing your money as well as talking about investing in property and other business instead of stocks.

If you want to do a really deep dive, Google the “FIRE movement” or “Financial Independence” and jump down that rabbit hole. (If you get easily overwhelmed, maybe save this for later. There’s a whole world of information out there, so it can be easy to feel like you just started drinking out of a firehose, but that also means there are plenty of resources to help you.)

I’m not a financial expert, but here’s my own two cents:

First, figure out where you stand. What do you have? What do you owe? Just knowing that can put you miles ahead of the crowd.

Second, open a savings account somewhere familiar (If you don’t have a checking account yet, open that first.) A “high-yield” savings account should give you 3-4% interest, so look for that. You might use the bank where you have your checking account or even the same company as your credit card. Starting somewhere you already know will make it easier to take that step, and if you want to switch banks later, you absolutely can.

Next, open an IRA. These are retirement accounts that you put your own money into and get tax benefits when you fund them. My general rule of thumb is: if you make less than $150,000 in a year, open a ROTH IRA. If you make more, open a Traditional IRA. If you’d like to learn more about those, there’s a good explanation here at DowJanes.com.

After that, use some of the links I’ve included to start looking at ways to increase your net worth. Whether that’s paying off debt, putting money into your savings account, or opening a brokerage account for investments, you’re working towards that goal.

As you’re setting financial goals, take a moment to think about what’s important to you. Imagine what your life looks like if you’ve got $100 in savings, or $1,000, or even $10,000.

Does that mean you won’t have to panic when your show closes with two weeks notice (or less) because you know you have enough to pay your bills for a few months while you look for another job?

It might look like taking on a passion project that you want to develop and love working on, even if it doesn’t pay much right now, and might grow into something later.

It could be realizing you’re in a toxic work environment and knowing you don’t have to stay in an unhealthy cycle while you look for another job.

It’s having a retirement account that’s accumulating quietly off to the side as political pundits debate if Social Security will still exist in 40 years.

Personally, having savings means I have freedom and my priorities are about making time for my family and my friends.

When I moved to the city, I made the decision to pay for an apartment that was bigger than I’d need just for myself, because it meant I had room for people to stay with me when they came to visit.

I could afford a vacation to meet my parents in London as they make the most of their retirement.

I can take time off to go visit old tour buddies in DC, Vegas, and Chicago or help my friend with her Christmas show in Pittsburgh.

The goal is to get to play as hard as I work. Sure, last year I didn’t have any vacation time from January to June because we were getting Outsiders up and running and then immediately went into Tony voting season. I didn’t mind it because I knew the expectations of the schedule and I like my job. (And that’s why I have the apartment. When I can’t get away, my friends are welcome to come to me.)

But that meant when we had subs trained, I made a point to follow through with plans and take time off to see people.

Recently, having that savings cushion (the FIRE community calls it “F-You Money,” which I do quite enjoy) meant that I made the decision to leave Outsiders this summer without a lot of extra worry. For some people, a hit show that’s going to run for at least a few years brings security and they’ll stick around for a while.

Honestly, I’m ready for the next challenge, and I planned ahead and talked to Cody (my designer) and made a plan. Part of that is getting the Outsiders tour set up. I’ve missed touring, so even just getting to go through tech and then handing it off to the crew will be a fun way to dip my toes back into that life.

Past that, there isn’t much of a plan. I’ll switch to being the sub on Outsiders and return as a sub for SIX (ah, that freelancing life!), and I’m looking forward to the change. I know I have the resources set aside so a couple months of light work isn’t a death sentence or anxiety inducing.

None of this would have been possible if I hadn’t started saving and investing while I was on the road.

And that’s what money gives you: freedom. It may not buy happiness, but it certainly does buy options. Everyone’s goals will look different, but do you and your future self a favor: get started on saving because there’s no better time than now.

Approaching Involvement

At this moment, many of us find ourselves living in states of uncertainty about the future of our industry, insecurity regarding our personal rights and safety, and concern about the conditions we live, recreate, travel, and work in. As these stressors have impacted us in familiar and unfamiliar ways, we may also find ourselves lonely, needing help, seeking protection, hoping to distract ourselves, or in dire need of support. We may feel burnt out, overwhelmed, or hopeless. We may find ourselves instinctively seeking out mutual aid, community, or affinity groups. We may also find ourselves wanting to give — to make an impact, defend those being attacked, encourage others, or be of service. We may feel pulled in multiple directions while struggling to satisfy our personal self-care needs.

If you feel any of these things right now, you’re not alone.

All of these impulses lead us to questions about changing our level of availability within, commitment to, and engagement with the world around us. Let’s not shy away from that. Instead, let’s think about how to approach community involvement better than we have in the past; if it’s more important now than ever, we should treat it that way. This blog is about a spectrum of community-centric skills we can use to effectively give and receive in the spaces we have available to us — whether those spaces manifest as local gatherings or wide-reaching online discourse.

We need to start somewhere, so let’s start with relationships. Nothing that I write below will work particularly well if you’re not ready to open yourself up to new people. Forging new relationships is difficult, but when the world changes, we need to change too. The other side of that openness to new relationships is adapting our personal roles based on what others bring to the table. Get comfortable with both of those ideas, especially if your instinct right now is to hunker down. I invite you to do the opposite — stretch out, take up more real estate, and connect. It’s scary, but you’ll feel better once you make the active decision to let yourself into the light rather than hiding from it.

So: how do we create a situation for ourselves in which we feel like we belong in a space and can thrive there, even when it feels like our world is falling apart?

The first step is taking a down-to-earth look at what your skills, talents, personality strengths, and proximity to resources are like. Taking stock will reveal a wealth of information about how you can naturally contribute to the types of causes or spaces that you resonate with. I encourage you to get away from the computer for a bit, grab a pen and paper, and brainstorm about the type of projects that you:

No matter where you come from, you have a role that is useful to the causes you care about. Maybe you’re not particularly skilled in XYZ, but you can do ABC passionately and effectively — and perhaps you’ll want to find a space where you can be mentored on XYZ. Your unique set of practiced and not-so-practiced skills is useful. Take ownership over that.

Now, here’s the thing: we can’t personally champion every single cause we care about. So when you do this, narrow it down to one, two, or three things. Maybe it’s trans rights. Maybe it’s creating educational material for underprivileged groups and fighting for climate justice. Maybe it’s addressing sexual harassment in the touring industry. Whatever the combination of things that you want to fight for, don’t hesitate to accept that the seed is there.

It might take a couple of days; sleep on it. Narrowing down what you value right now may take more than one sitting and maybe a talk or two with a trusted friend. But once you feel good about what you possess the energy to work on right now, great — we’ve got a seed to work with.

Second, let’s talk about different types of communities.

No group, cause, or non-profit can satisfy all of the things we as human beings need in our village to thrive. We need an array of different types of people, places, and resources in the same way a child needs variety in diet, caretakers, and social skills to grow up well-rounded and strong. We may need more of one thing than another based on our personality, too.

Let’s explore for a second what types of audio communities exist, no matter where we are in our careers:

While these might take different levels of importance depending on where we’re at, I believe that these categories — or any additional ones that came to mind as you went down the list — provide the balance of nourishment necessary for the seeds we individually bring to the garden.

But what if you can’t find fertile soil to begin with? What if you search and can’t find the space to germinate? Where do you turn to?

There are many lists of resources that exist to help you find those spaces, and I have accumulated some of those below for your exploration. But I think there’s a different issue here, and it starts with the general approach to searching. If you are struggling to find a place where you feel like you belong, sit with it in honesty and think about these things:

Looking for a space that’s right for you may take you down unexpected paths. Sometimes, those paths can be triggering, reintroduce you to people you found challenging to be around, or remind you of ways you’ve acted in the past that you weren’t proud of. All of this is a part of growing and getting to a place where we can show up.

Third, once we do find a space we feel good about showing up to, how do we navigate it from sunrise to sunset and through the night, too?

A common issue I see is that members of communities — myself included — don’t always take the time to understand the identities, perspectives, and context of the leaders of the organization. What is the structure? What are the limitations of the folks in charge, including time and money? What are fair expectations for their investment, and what are not? How are they nourished to optimize the sustainability of their efforts while nourishing everyone else? For example, if you find yourself getting critical that there aren’t enough events or training happening, or perhaps that the events don’t cover topics you think are important, then introduce solutions and assess what you need to make them happen. What you are looking to have in a community is likely something that is shared by others, so if you create something that you see a need for, others will probably recognize their own need for it, too.

Or, let yourself take the follower position — which is no less important than the leader(s)! — and support a project that you believe in without being at the forefront of the discussion.

Especially if you’re in the early part of your career like myself, you may find yourself wanting to be a part of projects that would involve you doing unpaid volunteer work that makes the world better. There’s a difference between that and what we typically think about as unpaid labor. I invite you to consider breaking out of an understanding of your effort based on capitalism and instead think about opening doors, preventing gatekeeping, and being in service. Think of the intangible things that we can exchange that have nothing to do with money. If something is nourishing your soul and keeping you afloat, what does it matter if you aren’t making money off of it? I invite you to approach any volunteer work you find yourself doing as a combination of love and effort that gives back to you in a different form of currency. If you can’t see it in a positive way, instead of as unpaid labor, you shouldn’t be volunteering your time or energy. Once you start to grow jaded about it, make room for someone else to take over.

Listen to how the operation functions, identify where the shortcomings are with an open mind that you might be the exact person to solve those problems, and gather your resources.

From there, maybe we can build a bigger garden slowly and carefully around one that already exists. Or maybe we need to plant our seeds next to someone else’s that are complementary to ours. Maybe we need to plant a few seeds that aren’t quite meant to make it before we get a good solid one sprouted.

Now that you’ve done some planning, asked some questions, and are working and making moves — no matter how small they are — let’s think about the fourth step.

Let’s say you’ve got a few organizations you’re a part of that you care about and are gradually finding your voice in. This is gonna sound harsh: you need to keep showing up. If you don’t show up, you’re not a participant — you’re just a member. You can’t benefit or contribute without showing up. Being associated with an organization and not participating means you’re not engaged. Showing up means you are acknowledging that joining that weekly Zoom call or being present at that yearly event is important to you and that you care. Sometimes you can’t, and that’s okay.

But sometimes, there are other factors besides work, family needs, meetings, or appointments that you’ll find preventing you from doing so. Let’s talk about it.

One thing I have struggled with in the past is showing up when I don’t feel 100%. Sometimes, you will only have the energy to show up 50%. Or even 25%. But hear me loud and clear: that’s when the magic happens. When you only have so much to give, when you need to delegate to accomplish something, or when you are clearly in need of support, that is when you feel the power of community. That is when you experience others’ gifts and learn to receive. That is when you experience how it feels to be on the other side of all the energy you put forward in your work. Through the various trials that individuals in a community are going through, we discover that we are all both leaders and followers in our own ways; it’s just that sometimes we find ourselves talking, and other times we need to be listening. When we go through extensive periods where we can’t seem to show up how we want to, we learn about what other people might need when they are struggling.

This is all a discovery process, and showing up regardless of how much your self-doubt or imposter syndrome insists you stay home is an important pattern to establish for your involvement now and in the future.

Showing up also includes reading, appreciating, listening to, or amplifying other people’s work. It means engaging not just by being present but knowing your interest and enthusiasm for what others around you are working on has a positive impact on them.

So…invest in others as you keep showing up!

Let’s review:

  1. acknowledge that something is needed and that you have skills that are important to that happening — which is exciting! (you have a seed)
  2. search for spaces that resonate, which may mean processing some discomfort or past experiences first (which is necessary for a healthy, safe spot of even ground to start)
  3. make moves thoughtfully and graciously to make a sustainable presence for yourself in this new space (strategize your seed sowing)
  4. keep showing up (monitoring for pests, watering, and adding nutrients) as time goes on even if you need to ask for help to do so

This isn’t the end of our little sprout’s story, of course, and there could another point that says: know when the season has ended.

Sometimes, our relationships with certain communities do need to end or be reduced in scope. That doesn’t necessarily mean that something dramatic or upsetting happened, but simply that it’s time to move on. Everything has a cycle, just like at our gigs: we all start somewhere and work our way up. As we move on, it is inevitable to leave certain things behind. While those situations can be saddening, that shift makes space for others to progress and form new relationships, too.

Keep on progressing as you explore what spaces are healthy for you and which ones aren’t, and trust your instinct about whether you need to pause first, process first, or get straight to work.

Rest assured that there are people all around you who feel the way you do and that we will most effectively survive this (waves into the air) together by making our voices heard and acknowledging our changing needs.

Below are some places to explore on your journey. Because of my background, many of these fall under the categories of live sound and/or theatre sound.

______________________________________

Communities, Organizations & Associations:

AES — https://aes2.org/

Association of Sound Designers in Production (UK) — https://www.associationofsounddesigners.com/

Audio Nerd Book Club — https://audionerdbookclub.org/

Black Theatre Network — https://www.blacktheatrenetwork.org/

OISTAT (Organization of International Scenographers, Theatre Architects, and Technicians) — https://oistat.org/

Themed Entertainment Association — https://www.teaconnect.org/

The Parity Database (NYC) — https://theparitydatabase.org/

TSDCA (Theatrical Sound Designers and Composers Association) — https://tsdca.org/

USITT (United States Institute of Theatre Technology) — https://www.usitt.org/

Wingspace NYC — https://wingspace.com/

Women’s Audio Mission — https://womensaudiomission.org/

Some Events and Networking Opportunities to Explore:

InfoComm — https://www.infocommshow.org/

Live Design International (LDI) Show — https://www.ldishow.com/

Prague Quadrennial (PQ) — https://pq.cz/

Sound Kitchen — http://www.sound-kitchen.net/

Organizations that can support you if you’re struggling right now:

Behind the Scenes Help — https://wp.behindthescenescharity.org/

Nami — https://www.nami.org/

Open Path Therapy — https://openpathcollective.org/

Therapy for Black Girls — https://therapyforblackgirls.com/

Trans Life Line — https://translifeline.org/

Trevor Project — https://www.thetrevorproject.org/

Production on Deck’s List of Databases — https://www.productionondeck.com/databases

^ This page is a treasure trove of resources with something for everyone, primarily consisting of contact directories for theatre artists.

Designing and Mixing My First Shows

Since becoming a theatre sound student last September, I’ve had the opportunity to work on two productions in two different spaces. The first was our Christmas pantomime, Rapunzel, and the second was one of the all-time great musicals, A Chorus Line.

First, Rapunzel. I was warned that I’d be thrown in the deep end on this one, and that was certainly true. It was one of the biggest shows of the year, running for two weeks in our 250-seat theatre. We had two shows a day for most of that time: schools performances in the morning and general public in the evening. As sound designer my work started in October, attending production meetings with the director, lighting designer and DSM and going to as many rehearsals as possible. In keeping with pantomime tradition, there were a lot of comical and bombastic sound effects required. One of the most fun to create was a bubbling, hissing cauldron in the witch’s lair. It involved blowing bubbles through a straw in a bowl of water, capturing the sound made by water coming into contact with a stovetop, mixing the two together and adding a lot of reverb! I was quite proud of how it turned out.

I’ll be honest: tech week was incredibly stressful, unlike anything I’ve ever experienced. I had to program a lot of pretty complex sequences in QLab which, considering I’d never done it before, was definitely one of my proudest achievements. There were various technical challenges to overcome and a few tensions along the way, which is to be expected during any tech run. I think it’s fair to say every department struggled with the first dress rehearsal. However, everything suddenly seemed to click into place afterwards and by the time we opened, everyone had found their flow.

As well as designing, I was also required to mix the show: something I know would not have been the case in a professional environment, but in this case we didn’t have the luxury of a larger sound department. My desk was a Yamaha QL5 and we had a cast of 19 actors and six dancers, with 14 radio mics at our disposal (swaps and breakages were involved). The moment of terror described by many theatre sound engineers just prior to their first ever show is now 100% relatable to me! Dress had gone well, soundcheck had gone well, but part of me was still thinking, “Is it too late to run away?” That nervous energy remained before each subsequent show, but I soon found I was able to channel it into pure focus as soon as the curtain went up. And when we got to bows, applause and cheers, that feeling of exhilaration would hit and I’d think: That’s why I wanted to do this!

The feedback I got from my tutors, the director, cast and my fellow crew, as well as the response from audiences, gave me confidence and assured me that all of the hard moments had been worth it. I certainly understand now why people say pantomime is one of the toughest things you can work on, but when it goes well, it’s so rewarding.

After Christmas it was straight into rehearsals for A Chorus Line. This show took place in our smaller studio theatre and was more straightforward in that there were no sound effects required, just tracks (and in this case QLab was operated by our DSM). I used an Allen & Heath analogue desk this time, so it was really good to get experience of a different setup. We had a cast of 15 and needed 14 radio mics and one handheld for the director character. Inevitably there were some breakages, which made mic swaps a bit of a challenge as the majority of the characters were on stage most of the time, with no interval. It was a bit easier later on in the show, as we had solos from Diana, Cassie and Paul which provided more opportunity for swaps.

My biggest takeaways from these two experiences have been:

X